
Business Plan Review: Find Out If Your Plan Will Survive the Funder
You have a plan. It took weeks, or it cost money, or both. The question now is not whether it reads well. It is whether the person assessing it will fund it.
Most plans that get rejected are not rejected because the business is weak. They are rejected because the document answers questions the funder was not asking and leaves unanswered the three or four they always ask. A plan written for a general audience persuades a bank credit team, a Start Up Loans adviser, and a seed investor equally poorly, because each is reading for something completely different.
We also review plans written for the Innovator Founder visa. An endorsing body will judge whether your business is innovative, viable and scalable before your application reaches the Home Office. We tell you whether your plan meets that standard before you pay the endorsement fee.
We review plans that have already been written, whoever wrote them. A template, a freelancer, an AI tool, an in-house draft or a previous consultant. Start with a free health check. If the plan is close, we will tell you what to change. If it is not, we will tell you that too, and what it would cost to fix.
Since 2014, we have advised more than 2,000 businesses and facilitated over £250 million in funding, achieving a 90 per cent success rate compared with an industry average of 13 to 20 per cent. We know what the assessors are looking for because we write to their criteria every week.
Who Delivers This Service
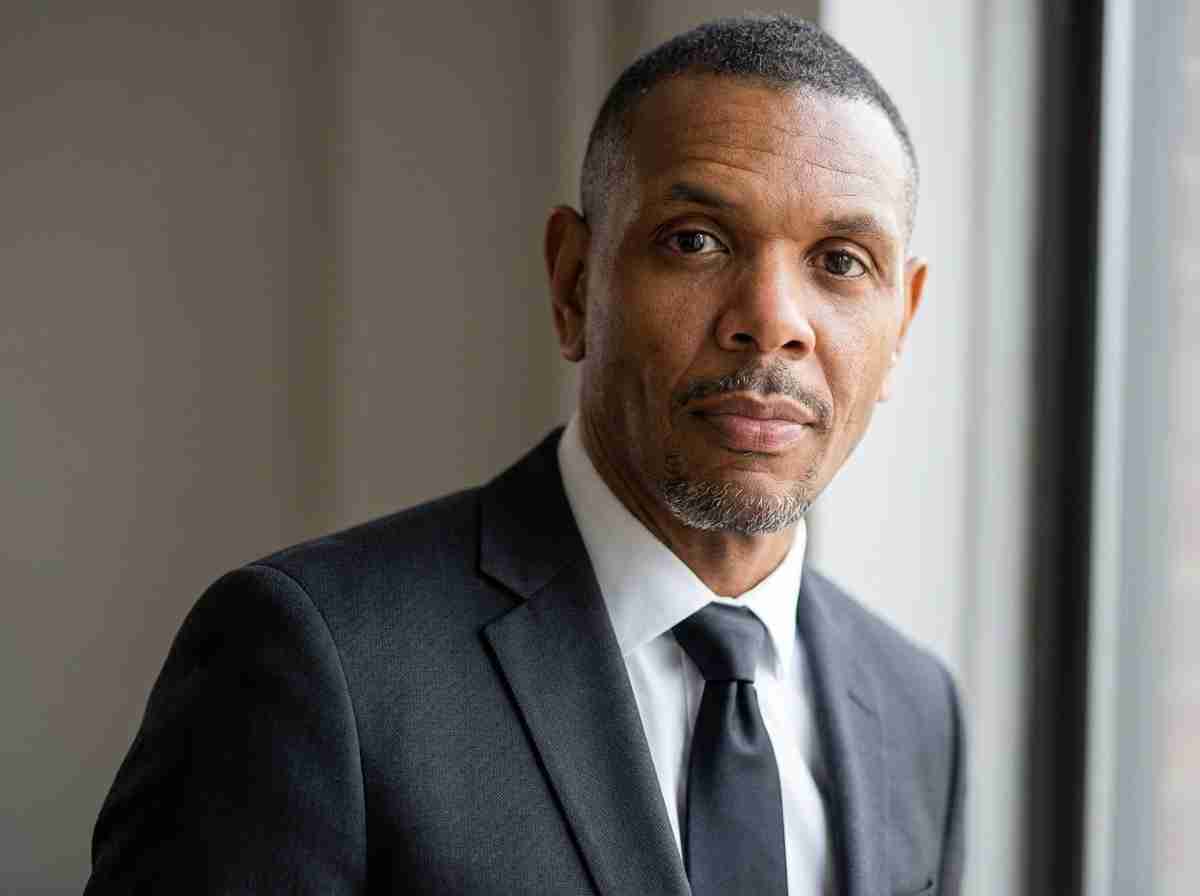
Reviews are led by Kurt Graver, Founder and Managing Director of SGI Consultants, an ACCA-qualified accountant with an MBA and a Certified Business Mentor with the IOEE. Reviews are carried out by senior consultants who write to these funders’ criteria, not by a junior analyst working from a checklist or by an AI tool.
That is the difference between being told your plan needs a stronger market section and being told which two assumptions a credit team will challenge and what evidence will close them.
Business Plan Writing Track Record
We don't rely on theory. We rely on a track record of securing capital from some of the world's most demanding lenders & financial institutions
2,000+
Clients supported
90%
Funding success rate
£250M+
Funding secured
£850k
Average investment secured on investor-ready engagements
Free Plan Health Check
Send us your plan and the funder you are targeting. Within three working days, you will receive a one-page assessment scoring the plan against 10 criteria, with a traffic light on each, an overall verdict on whether it is submission-ready, and the three weaknesses most likely to cost you the decision.
What it does. It tells you where the plan is failing and how serious it is. For a lot of people, that is enough to know whether to submit, revise or stop.
What it does not do. It does not tell you how to fix anything. The scoring identifies the problems; the paid review explains the causes and provides specific changes. We are direct about that line rather than pretending the free version is a full assessment.
Conditions. One free check per business. Business plans only, not financial models on their own. You need to name the funder or scheme you are applying to, because a plan cannot be assessed in the abstract. We do not share your plan with anyone, and we do not add you to a mailing list without asking.
The 10 criteria we score against
The same framework applies to every plan, but the weighting shifts depending on who is reading it.
# | Criterion | What we are testing |
|---|---|---|
1 | Funder fit | Is the plan written for the specific decision-maker, or for a general audience |
2 | Executive summary | Does it answer the funder’s first three questions on the first page |
3 | Market evidence | Is the market sized from sources, or asserted |
4 | Competitive position | Are competitors named and analysed, or waved at |
5 | Financial logic | Do the numbers reconcile to the narrative, line by line |
6 | Forecast defensibility | Is there an assumption log, are the drivers visible, does it survive a change of input |
7 | Serviceability or return | Debt cover for lenders, unit economics and scalability for investors |
8 | Risk treatment | Are the real risks named and mitigated, or only the comfortable ones |
9 | Management credibility | Is the team’s relevance evidenced, or listed |
10 | Criteria compliance | Does the plan map to the published scoring rubric where one exists |
What shifts by funder
A bank credit team weighs serviceability, security, and forecast realism and will not read past a cash flow that does not cover the repayment. A grant assessor scores against a published rubric, so a plan that does not map to it loses marks it never needed to lose. An investor tests to check consistency among the deck, the plan, and the model, and treats any discrepancy as a signal about the founder rather than the document.
A Start Up Loans adviser is running something closer to a credit process than an investment one, and needs a personal survival budget that works. The Home Office and the endorsing body assess against the innovation, viability and scalability criteria in that order.
Endorsing bodies focus less on repayment and more on whether the idea is new, whether you can deliver it, and whether it can grow. A plan written for a bank will often fail to be endorsed, and the reverse is also true.
Innovator Founder visa business plan review
Many visa plans now arrive written with AI tools. They read well but fail on the points an endorsing body checks first. We score your plan against the three endorsement tests and the evidence behind each one:
| Test | What the assessor looks for | Where AI-written plans usually fall short |
|---|---|---|
| Innovative | A genuinely new idea or a real advantage over what is already available | General claims about being different, with no proof |
| Viable | The skills, resources and market to make the business work | Market figures with no source, and costs that don't match the plan |
| Scalable | A credible route to growth, jobs and expansion | Job forecasts that the financial model doesn't support |
You receive the same verdict as any review: submit, revise, or rethink. If the plan needs work, the £250 review fee counts towards any fix taken within 30 days.
We review the business case only. We do not give immigration advice. If you need advice on eligibility or your application, speak to a regulated immigration adviser or solicitor, and we can work alongside them.
Request your free plan health check
Business Plan Review Packages
Full Business Plan Review, £250
A written review of the complete plan against the criteria your specific funder applies, delivered in five working days.
- Scored assessment across all 10 criteria with the reasoning behind each score
- Section-by-section commentary identifying what is missing, what is unsupported and what will be challenged
- A prioritised fix list, ordered by what will move the decision rather than by what appears first in the document
- A verdict on whether to submit as is, revise, or change funder
- A 45-minute debrief call to work through the findings and your questions
If you also want the financial model examined, add the Forecast Review below. Most rejections that survive a good narrative are caused by the model, so for anything above a Start Up Loan we usually recommend both.
The fee is credited in full against any remediation package taken within 30 days. If you decide to have us make the changes, you are not paying twice.
Forecast Review and Rebuild, £295
For plans where the narrative is sound but the numbers are the exposure. We examine the model for internal consistency, reconciliation with the narrative, assumption quality, and its robustness to changes in the inputs that matter. Where the model cannot be salvaged, we rebuild it: three- or five-year profit and loss, cash flow and balance sheet, with a visible assumption log, working sensitivity toggles and the debt cover or unit economics the funder will test. Delivered as an editable Excel file that you own.
Remediation packages
If the review finds problems you want us to fix rather than fix yourself, there are three routes. All three are quoted after the review, because the honest price depends on what the review actually found.
Package | From | For plans where | What we do |
|---|---|---|---|
Targeted Remediation | £600 | The plan is broadly sound, and two or three sections are letting it down | Up to three named sections rewritten to the standard your funder expects, reintegrated so the plan still reads as one document. One revision round. Five working days |
Full Rebuild | £1,200 | The structure is wrong for the funder, or the plan was written before the funding route was decided | The plan was restructured and rewritten end-to-end around the right decision-maker, retaining the research and content that work. Two revision rounds. 10 to 15 working days |
Rebuild plus Financials | £1,750 | Both the narrative and the model need work, and the two do not currently agree | Full Rebuild plus a rebuilt five-year model with sensitivity analysis, reconciled line-by-line to the narrative. Two revision rounds. 15 to 20 working days |
Remediation is cheaper than a fresh plan because the research and the thinking already exist. That is the whole reason this service is priced the way it is.
When we will tell you to start again
Sometimes remediation is the more expensive route, and we will say so rather than take the work. Three situations where that happens.
The plan is a template with nothing underneath it. If the market section is generic, the competitors are unnamed, and the financials are placeholder growth curves, there is nothing to remediate. Rewriting every section is a fresh write, and we will quote it as a single unit.
The business is not yet fundable. No document fixes insufficient trading history, a credit issue, or a proposition that has not been tested with a customer. We will tell you what needs to change in the business and when to come back, which is more useful than a better-looking rejection.
You are targeting the wrong funder. A plan is frequently fine and aimed at a route the business will never qualify for. In that case, the fix is the funding strategy, not the document, and the conversation moves to our funding service.
We decline engagements where the business is not ready. That discipline is a large part of why our success rate is what it is.
Turnaround
Service | Turnaround |
|---|---|
Free Plan Health Check | Three working days |
Full Business Plan Review | Five working days, including the debrief call |
Forecast Review and Rebuild | Five to seven working days |
Targeted Remediation | Five working days |
Full Rebuild | 10 to 15 working days |
Rebuild plus Financials | 15 to 20 working days |
Book A Free Business Plan Health Check
Frequently Asked Questions (FAQs)
Yes, and no call is required to get it. Send the plan, name the funder, and you receive a scored one-page assessment within three working days. It is limited to one per business and deliberately stops short of telling you how to fix what it finds because that is the paid review. We would rather be clear about that line than have you feel the free version was a sales device.
That is the point of the service. We review plans written by templates, freelancers, AI tools, in-house teams and other consultancies. We have no interest in whether the original author did a good job, only in whether the document will get you funded.
Usually not the writing, which is often fine. The problems are consistent: market figures that are unsourced and don't withstand scrutiny, competitors described generically, financial projections shaped like a plausible curve rather than built from your actual drivers, and no mapping to the specific criteria the assessor is scoring against. A funder reads hundreds of applications and quickly recognises the pattern. Our review tells you which of these apply to yours.
Yes. We score it against the innovative, viable and scalable tests that endorsing bodies apply, and tell you which sections an assessor is likely to challenge. We review the business case, not your immigration eligibility.
Not in itself. The risk is generic content and figures that don't add up, which assessors spot quickly. The free health check shows you where your plan stands before you apply.