
Franchise Business Plans UK - Acquisition & Expansion
Franchisors don't want entrepreneurs. They want operators.
Securing franchise approval is not about demonstrating entrepreneurial vision, market insight, or innovative thinking. It is about proving three things with evidence: that you have the liquid capital to survive the ramp-up period, that you will execute the franchise system with fidelity rather than attempting to improve it, and that your proposed territory has the demographics and footfall to support the brand's required unit volumes.
Franchisors reject 60–70% of prospective franchisees during the application process — almost never for lack of enthusiasm, almost always for documentation issues.
Most business plan writers approach franchise applications as they would startup pitches. They emphasise the applicant's entrepreneurial background, their vision for the business, and their growth ambitions. Franchisors find this actively off-putting.
A Costa Coffee development manager reviewing 40 applications in a week is not looking for the most creative pitch — they are looking for the safest operator.
The plan that wins approval demonstrates financial resilience, operational understanding of the franchise system, and credible territory analysis grounded in the franchisor's own Average Unit Volume benchmarks.
SGI Consultants has spent 12 years specialising in franchise business plans. We have supported the establishment of more than 400 franchise locations across Costa Coffee, KFC, Subway, McDonald's, Domino's, Papa John's, Vodafone, Toni & Guy, Kumon, Bluebird Care, and Fantastic Services, among many others.
We understand what each major franchisor's development team looks for in an application — because we have submitted applications to them repeatedly and know which ones advance to the next stage and which do not.
Our overall franchise approval rate is 88%, rising to 90% for established Tier 2 brands and 92% for emerging franchise systems.
Who Delivers This Service
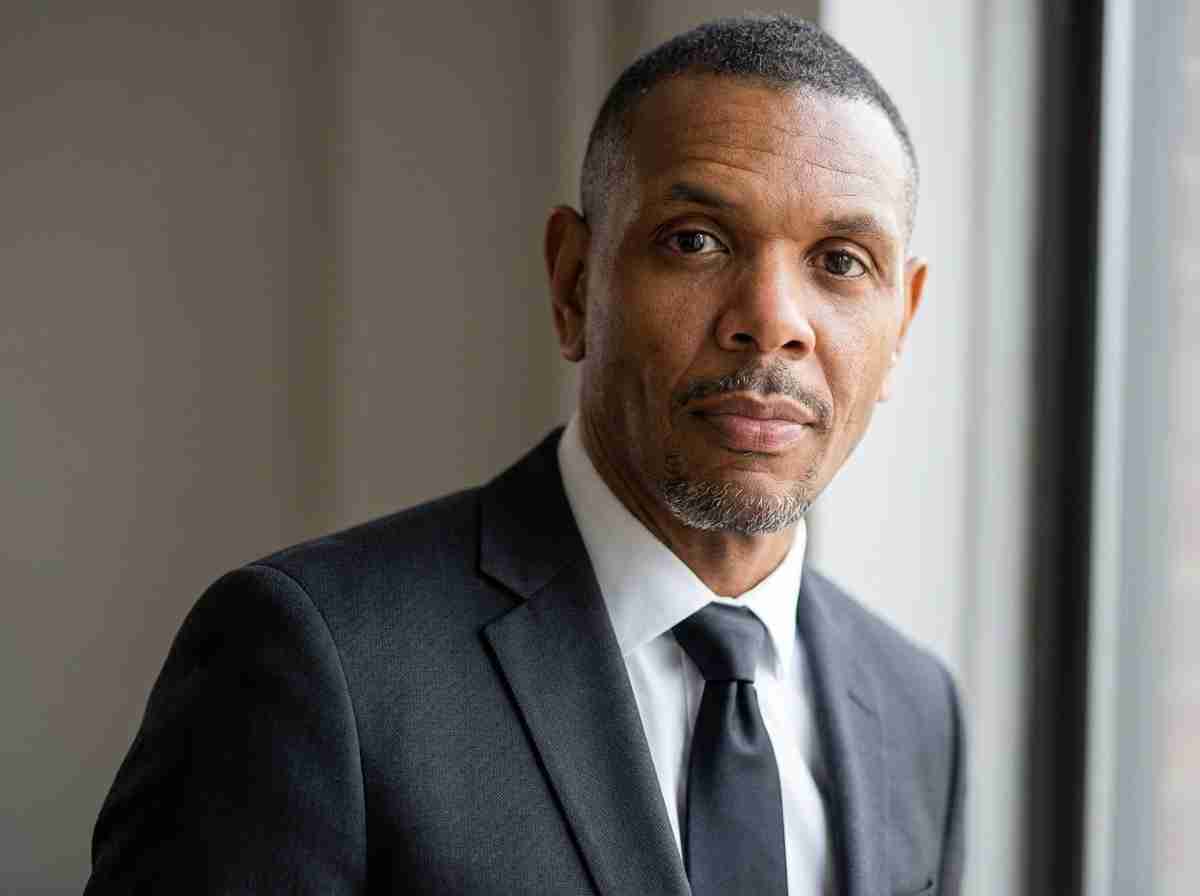
Your franchise business plan will be led by Kurt Graver — Accountant, MBA, Founder of SGI Consultants — supported by a qualified team with experience across single-unit acquisition, multi-site expansion, and franchisor approval processes. Kurt personally oversees every franchise engagement.
Proven Success Across Major Franchise Brands
We don't guess at franchisor requirements. We rely on a track record of successful franchise approvals across the UK's most demanding brands.
Franchise Locations Established
Franchise Approval Rate (First Application)
Total Capital Deployed Across Franchise Projects
of Specialist Franchise Planning Experience
Brands We've Supported



Explore detailed examples of how our business planning has enabled clients to secure funding and achieve growth:
Why Franchise Applications Get Rejected — And What We Do Differently
Generic business plan writers fail franchise applications for a predictable reason: they apply the same framework they use for bank loan applications or investor pitches. The language, the emphasis, and the financial modelling approach are all wrong for a franchise context.
Franchise consultants and business advisers who work within specific brand systems often understand their franchisor's requirements in depth — but they lack the financial modelling capability to produce the territory analysis, multi-scenario projections, and bank-ready documentation that a major franchise application requires. They can advise on the brand; they cannot always produce the documentation.
A franchisor-supplied template or an FDD-based self-prepared plan signals to the development team that the applicant has not invested seriously in their application. Major brands receive hundreds of applications from candidates who have simply completed the standard forms. A professionally prepared, brand-specific franchise business plan stands out before the development manager reads the first page — and it demonstrates the operational seriousness that franchisors look for in an approved partner.
SGI sits between these options. We have the financial modelling depth to build territory analyses grounded in the franchisor's actual Average Unit Volume data, the sector knowledge to speak the brand's language, and the experience of having submitted applications to each major UK franchisor, so we know what their development teams actually want to see. Our franchise business plans are also structured to double as the bank lending application most franchisees will need — because most franchise investments are part-funded through franchise-specialist lenders, and the same documentation serves both purposes when built correctly.
Who We Work With
Franchise applicants come to us at different stages, with varying levels of experience and target brands. The documentation requirements vary substantially based on the franchisor's tier, the applicant's background, and whether a single-unit or multi-unit agreement is sought.
First-time franchisees entering major brands. You are applying to a Tier 1 or Tier 2 franchise — Costa, Subway, Domino's, Anytime Fitness — for the first time, likely without previous franchise experience. These franchisors require comprehensive business plans, including territory analysis, personal financial statements, evidence of liquid capital, and operational plans that demonstrate your understanding of what operating the brand entails. We provide the documentation that compensates for limited franchise history by demonstrating financial strength, relevant transferable experience, and clear operational planning.
Experienced franchisees expanding within a brand. You have one or more successfully operating units and are applying for additional territory, a multi-unit development agreement, or an Area Development Agreement granting exclusive territorial rights. The documentation challenge shifts: you need to demonstrate that your management infrastructure can scale alongside the additional units without compromising standards at your existing locations. We build the phased development plan, area management structure, and consolidated financial model required for multi-unit applications.
Investors acquiring an existing franchise unit. You are purchasing a resale franchise — an existing unit from an outgoing franchisee — which requires a Conversion or Acquisition Plan that addresses the unit's historical trading performance, the transition strategy, the franchisor's refranchising approval process, and typically a bank lending application to fund the acquisition. We produce all of these simultaneously, with the financial analysis structured to satisfy both the franchisor's refranchising criteria and the lender's credit assessment.
International operators entering the UK market. You operate a franchise internationally and are applying to bring a brand to the UK, or you are an overseas entrepreneur applying for a UK franchise unit as part of an Innovator Founder or Expansion Worker Visa application. The documentation requirements combine the standard franchise application with the immigration-compliance elements required by the visa route. We produce integrated documentation that satisfies both the franchisor and the Home Office simultaneously.
Entrepreneurs are evaluating franchise options before committing. You are in the research phase — you have a budget, a location preference, and a shortlist of brands, but you have not yet committed to a specific franchise system. We provide pre-application guidance on which brands align with your capital position, location, and operational background, and we can produce initial financial modelling to compare projected returns across franchise options before you approach any brand.
Franchisors are seeking to develop their franchisee documentation standards. You are a franchisor or master franchisee who wants to provide prospective franchisees with a documentation framework or to raise the quality of incoming applications from your pipeline. We work with franchisors to develop application documentation standards and provide planning support to applicants at the franchisor's referral.
If your situation is not described above, contact us. We work across all franchise sectors and all stages of the franchise lifecycle.
Tailored Franchise Business Plans for Every Model
Different franchise sectors have distinct approval criteria, financial thresholds, and documentation expectations. A QSR franchisor's development team and a home services franchise's approval process are not comparable — the territory analysis, staffing model, and break-even horizon differ. We build each plan around the specific requirements of the target brand and sector.
1. Quick-Service Restaurant (QSR) Franchise Plans
90% approval rate for Tier 2 brands | 85% for Tier 1 (McDonald's, KFC, Costa)
The Objective: Secure approval from major food service franchisors to operate branded restaurants and quick-service outlets.
The SGI Approach: QSR franchisors assess Location Analysis and Operational Experience above all other factors. We conduct detailed demographic studies using professional data sources to demonstrate that your territory can support the franchisor's required Average Unit Volume (AUV)—the weekly or monthly sales threshold used to determine whether a unit is viable. We benchmark projected revenues against the franchisor's published or disclosed AUV data, build a conservative break-even model (typically 18–24 months for a new QSR unit), and document relevant hospitality management experience or, where this is absent, a credible plan for recruiting an experienced store manager before opening.
Key components: site selection analysis (footfall data, demographics, competitive mapping), AUV-based revenue projections, a staffing plan aligned with the franchise operating manual, a conservative break-even analysis, and personal liquid capital verification.
Ideal for: Costa Coffee, Subway, McDonald's, KFC, Domino's, Papa John's, Blacksheep Coffee, Baskin-Robbins, ITSU, Greggs.
2. Fitness & Wellness Franchise Plans
85% approval rate for applicants with suitable premises identified
The Objective: Secure approval to operate branded gyms, fitness studios, or wellness centres.
The SGI Approach: Fitness franchisors assess Member Acquisition Capacity alongside Facility Investment and Operator Experience. The financial model is driven by a membership ramp-up curve — how long it takes to reach the break-even membership level — which we calibrate conservatively using the brand's performance data from comparable locations. We document the facility specification and fit-out investment to confirm compliance with brand standards, and, where the applicant plans a pre-sale membership campaign, we model the pre-opening revenue and its impact on initial cash requirements.
Key components: local market analysis (population density, income levels, competitor audit), membership ramp-up financial model (typically 12–18 months to break-even), facility specification and fit-out budget, pre-sale membership campaign plan, and personal capital adequacy verification.
Ideal for: Anytime Fitness, Snap Fitness, Energie Fitness, Orangetheory, F45, PureGym franchise options.
3. Retail Franchise Plans
87% approval rate for prime high-street and shopping centre locations
The Objective: Secure approval to operate branded retail stores in high-street, shopping centre, or retail park locations.
The SGI Approach: Retail franchisors prioritise Location Quality and Retail Management Experience. We provide detailed catchment area analysis — using footfall data, consumer spending power metrics, and competitive retail mapping — to demonstrate that the proposed location can generate the franchisor's minimum required sales volumes. The financial model is built on seasonal trading patterns that reflect the retail calendar, and we document the applicant's retail background or, where this is absent, a specific recruitment plan for an experienced retail manager.
Key components: catchment-area demographics and spending-power analysis, footfall data and conversion assumptions, product mix aligned with franchisor guidelines, seasonal trading-pattern modelling, lease terms and fit-out investment.
Ideal for: Clarks, Card Factory, Cash Converters, Snappy Snaps, Mail Boxes Etc, The Body Shop.
4. Professional & Home Services Franchise Plans
92% approval rate — lower barriers, strong recurring revenue models
The Objective: Secure approval to operate franchise businesses in professional services, education, home services, or care sectors.
The SGI Approach: Professional and home services franchises typically have lower capital requirements than QSR or retail, but their financial models are driven by client acquisition ramp-up and recurring revenue growth rather than footfall or unit volume. We build client-acquisition models grounded in the franchisor's typical ramp-up data, demonstrate the value of territory exclusivity, and structure the operational plan around the management-time requirements of the specific franchise model — particularly important for owner-operator models, where the franchisee's personal time commitment is a key variable in the financial projections.
Key components: client acquisition model with a ramp-up curve, territory exclusivity and demographic analysis, recurring revenue build-up projections, operational time-commitment planning, training completion and launch timeline.
Ideal for: Kumon, TaxAssist Accountants, Red Driving School, The Travel Franchise, Bluebird Care, Fantastic Services, Molly Maid, Chips Away.
5. Multi-Unit Development Plans
82% approval rate for applicants with a proven single-unit track record
The Objective: Secure approval for multi-unit franchise agreements, Area Development Agreements (ADAs), or master franchise rights covering multiple territories.
The SGI Approach: Multi-unit and area development agreements require demonstrating Scalability and Management Infrastructure as much as financial capacity. The documentation must show how you will maintain operational standards at your existing units while simultaneously opening new locations — and how your management structure will evolve to support the portfolio as it grows. We model the phased rollout schedule, build a consolidated financial model covering all units in the development plan, and document the area management structure required by the franchisor's compliance team before granting exclusivity for a territory.
Key components: a phased development schedule (typically 3–5 years), a multi-unit financial consolidation model, an area management structure and reporting lines, a capital deployment timeline, and territory-by-territory viability analysis.
Ideal for: experienced franchisees expanding within an existing brand, investors building multi-brand franchise portfolios, operators entering Area Development Agreements.
Franchise Financing: Your Business Plan as a Bank Lending Application
The majority of franchise investments in the UK are part-funded through debt. Most major franchisors expect franchisees to fund 30–50% of the total investment from personal liquid capital, with the remainder financed through a bank loan or specialist franchise lender. NatWest, HSBC, and Lloyds all have dedicated franchise lending teams. Specialist lenders, including Franchise Finance and The Franchise Finance Company, have established lending relationships with most major UK franchise brands.
The critical point that many franchise applicants do not realise until they are in the process is that the franchise business plan and the bank lending application are effectively the same document — or they should be. A franchise business plan that demonstrates AUV-based viability to a franchisor's development team is precisely the financial model a bank franchise lending manager needs to see. A plan that tells one story to the franchisor and another to the bank creates credibility problems for both.
Every SGI franchise business plan is built to serve both audiences simultaneously. The financial model demonstrates cash-flow serviceability to the lender and territory viability to the franchisor. The personal financial statement satisfies the bank's capital adequacy assessment and the franchisor's liquid capital requirement. The operational plan demonstrates the bank's management capability assessment and the franchisor's systems adherence requirement. We structure this integration from the start of the
Book A Strategic Assessment and Business Plan Evaluation
Franchise Business Plan Pricing
We charge flat professional fees based on the complexity of your franchise model and the number of units you're applying for. Franchise business plans are more standardised than investor or grant plans, which allows us to offer competitive pricing.
From
Single-Unit Franchise Plan
- Franchisor-compliant business plan
- 3-year financial projections
- Location/territory analysis
- Personal financial statement
- Franchisor-specific formatting
- 7-10 days delivery
From
Premium Single-Unit Plan
- Comprehensive franchise plan
- 5-year financial model
- Deep-dive demographic analysis
- Competitive market assessment
- Detailed staffing and operations plan
- Multiple location comparison (if applicable)
- 10-14 days delivery
Multi-Unit Development Plan
- Multi-unit franchise plan
- Phased development schedule (3-5 years)
- Consolidated financial projections
- Area management structure
- Multiple territory analyses
- Capital deployment timeline
- 14-21 days delivery
Conversion/Acquisition Plan
- Existing franchise purchase or conversion plan
- Historical performance analysis
- Transition strategy
- Vendor due diligence support
- Financing coordination
- 10-14 days delivery
What's Included in Your Investor Business Plan Package
All Franchise Business Plans Include | Premium & Multi-Unit Also Include | Multi-Unit Only Includes |
|
|
|
Explore Further
Related reading:
- Franchise Business Success: Key Strategies to Know — Our franchise business blueprint covering the full acquisition and growth process
- Business Plans: Insights from 500 Evaluated Cases — What lenders look for when assessing franchise applications
- Market Entry Strategy Guide for Entrepreneurs — Strategic Considerations When Entering a New Market Through Franchising
Free resource:
- The Business Plan Template Masterpack → — Includes a franchise-specific business plan template
Content hub:
- Business Planning & Strategy Hub → — Strategic planning resources for franchisees and franchisors
Related services:
- Business Plan Writers — All business plan types covered
- Bank Loan Business Plans — Most franchise acquisitions are funded through commercial lending
- Business Funding Service — We manage the full funding facilitation process
Don't Risk Rejection Due to Poor Documentation
Franchise opportunities with major brands are competitive. Most Tier 1 franchisors maintain waiting lists of qualified applicants. If your documentation is weak — if the territory analysis is not grounded in the brand's AUV data, if the financial model does not demonstrate adequate liquid capital and break-even viability, or if the operational plan signals that you have not studied the franchise agreement — they will move to the next candidate.
Schedule a Free Franchise Approval Assessment today. In this consultation, we will review your target franchise, assess your financial position against the brand's specific capital requirements, and map out exactly what documentation your application needs to maximise the probability of approval.
If your financial position does not currently meet the brand's requirements, we will tell you that directly rather than take a fee to produce documentation that will not succeed.
Frequently Asked Questions (FAQs)
Most major franchisors require, at a minimum, a financial projections document and a personal financial statement. The depth of documentation required varies by brand tier. Tier 1 franchisors (McDonald's, KFC, Costa) require comprehensive business plans — territory analysis, operational plan, multi-year financial model, and personal financial history. Tier 2 franchisors (Subway, Domino's, Snap Fitness) typically require a solid business plan and financial model, but with less historical depth than Tier 1 franchisors. Tier 3 and emerging brands may accept simplified projections.
For multi-unit and Area Development Agreements at any tier, a full development plan with consolidated multi-unit financial modelling is always required. We tailor the depth of documentation to the specific requirements of your target franchisor.
The majority of franchise investments are part-funded by debt — typically 50–70% of the total investment, with the balance provided by the franchisee's liquid capital. The documentation a bank franchise lending manager needs is substantively the same as that required by the franchisor's development team: a territory analysis grounded in the brand's AUV data, a cash flow model demonstrating serviceability, a personal financial statement, and evidence of relevant operational experience.
We build every franchise business plan to serve both audiences from the outset — not as two separate documents, but as a single integrated application that satisfies the franchisor's approval criteria and the bank's credit assessment simultaneously. This is particularly important because the financial projections in the two documents must be consistent: a plan that shows one set of revenue projections to the franchisor and another to the bank creates immediate credibility problems with both.
We have established relationships with specialist franchise lenders and can provide introductions where bank financing is needed as part of the overall franchise investment structure.
Our primary service is documentation development—preparing you for franchisor approval. However, during the consultation, we can provide general guidance on which franchise models are best suited to your capital, experience, and location
To build a credible franchise business plan, we typically need: a personal financial statement (assets, liabilities, net worth), bank statements (6 to 12 months), tax returns or accounts (two years if self-employed or business-owning), property valuations if using property as collateral, any existing bank pre-approval letters, and the franchisor's Franchise Disclosure Document or franchise information pack.
We provide a structured questionnaire that makes the information-gathering process straightforward. You do not need to have everything organised before contacting us — we can identify any gaps during the initial consultation.
This varies dramatically by brand:
QSR (Quick-Service Restaurant):
- Small brands: £50k-£100k liquid
- Major brands: £150k-£300k liquid
- Total investment: £200k-£500k
Fitness:
- Budget gyms: £75k-£150k liquid
- Premium studios: £100k-£200k liquid
- Total investment: £150k-£400k
Retail:
- Card/gift shops: £30k-£75k liquid
- Apparel: £50k-£150k liquid
- Total investment: £75k-£300k
The "liquid capital" requirement is typically 30-50% of total investment, with the remainder financed.
Yes. While our primary service is business plan development, we have relationships with specialist franchise lenders and can provide introductions.
The franchise business plan we create is designed to be "bank-ready" for franchise lending applications.
If rejection is due to deficiencies in the business plan (not financial capability or location issues), we provide a complimentary revision to address the franchisor's concerns.
However, most rejections stem from:
- Insufficient liquid capital (we can't solve this)
- Poor location (we can help find alternative sites)
- Weak personal background (we can help position your strengths)
Timeline varies significantly by brand. Fast-track brands (Subway, Snap Fitness) typically complete the approval process in two to four weeks. Standard-process brands (Costa, Domino's, Anytime Fitness) take six to eight weeks. The most rigorous brands (McDonald's, KFC) run approval processes lasting 10 to 16 weeks that include multiple interviews, financial background checks, and operational assessments.
Our franchise business plan is typically ready in 7 to 14 days, depending on tier and complexity, so we are not the bottleneck. The franchisor's internal process determines the overall timeline from first contact to approved agreement.
Yes. We offer a Franchise Plan Update Service for existing franchisees who need to refresh their business plan for:
- Bank refinancing or additional lending
- Multi-unit expansion applications
- Franchise renewal negotiations
- Sale to prospective buyers
This is typically 30-50% less expensive than creating a new plan from scratch.
Yes. Our Multi-Unit Development Plan service supports:
- Multi-unit agreements (3-10 locations)
- Area development agreements (exclusive territory)
- Master franchise agreements (sub-franchising rights)
These are complex arrangements requiring sophisticated financial modelling and legal coordination with franchise attorneys.
Tier 1 (Major Brands - McDonald's, KFC, Costa): 85%
- Higher requirements, more scrutiny
- Clients typically have prior franchise or retail experience
Tier 2 (Established Brands - Subway, Snap Fitness, Domino's): 90%
- Moderate requirements
- Accept first-time franchisees with strong financials
Tier 3 (Emerging Brands): 92%
- Lower barriers to entry
- More flexible on experience and capital
Overall blended approval rate: 88%
The Franchise Disclosure Document (FDD) — or in the UK context, the franchise agreement and accompanying disclosure materials — contains the financial performance data, fee structures, territorial rights, and operational obligations that the franchisor provides to prospective franchisees. It is the primary reference document for building a franchise business plan.
The AUV (Average Unit Volume) data disclosed in the FDD is the foundation of credible revenue projections. Franchise business plans that project revenues significantly above the FDD's disclosed AUV data will be challenged immediately by both the franchisor and any bank lender. We work from the FDD data directly and build projections that are conservative relative to the network average — demonstrating financial prudence rather than optimism.