
Investor Readiness Preparation UK - Pre-Seed to Series A
Investor readiness preparation is a structured 10 to 16-week programme that builds every asset investors will evaluate during their due diligence process. Most UK funding rounds do not fail because of a weak idea; they fail because the financial model breaks under scrutiny, the pitch deck and the model tell different stories, or the founders cannot answer the questions that diligence inevitably surfaces.
We work with founders raising pre-seed angel rounds (£250K to £1M), seed institutional rounds (£1M to £4M), and Series A and beyond (£4M+). Engagements are sequenced as a project: business model validation, integrated 3-statement financial model, pitch deck, investment memorandum, due diligence question bank, valuation guidance, investor targeting, and structured fundraising timeline management. The deliverables collectively form what investors and their analysts assess; we build them into a single, consistent narrative rather than separate documents.
Across our engagements, founders raising in this way have closed rounds with Atomico, Balderton Capital, Index Ventures, Octopus Ventures, Seedcamp, LocalGlobe, and angel networks including SFC Capital, OION, and Cambridge Angels. The 73% funding completion rate is grounded in one principle: the financial model, pitch deck, and investment memorandum must tell exactly the same story.
Book a free 45-minute investor readiness audit. We will review existing materials if you have them, identify the gaps that would block due diligence, and tell you whether you are ready to raise.
Who Delivers This Service
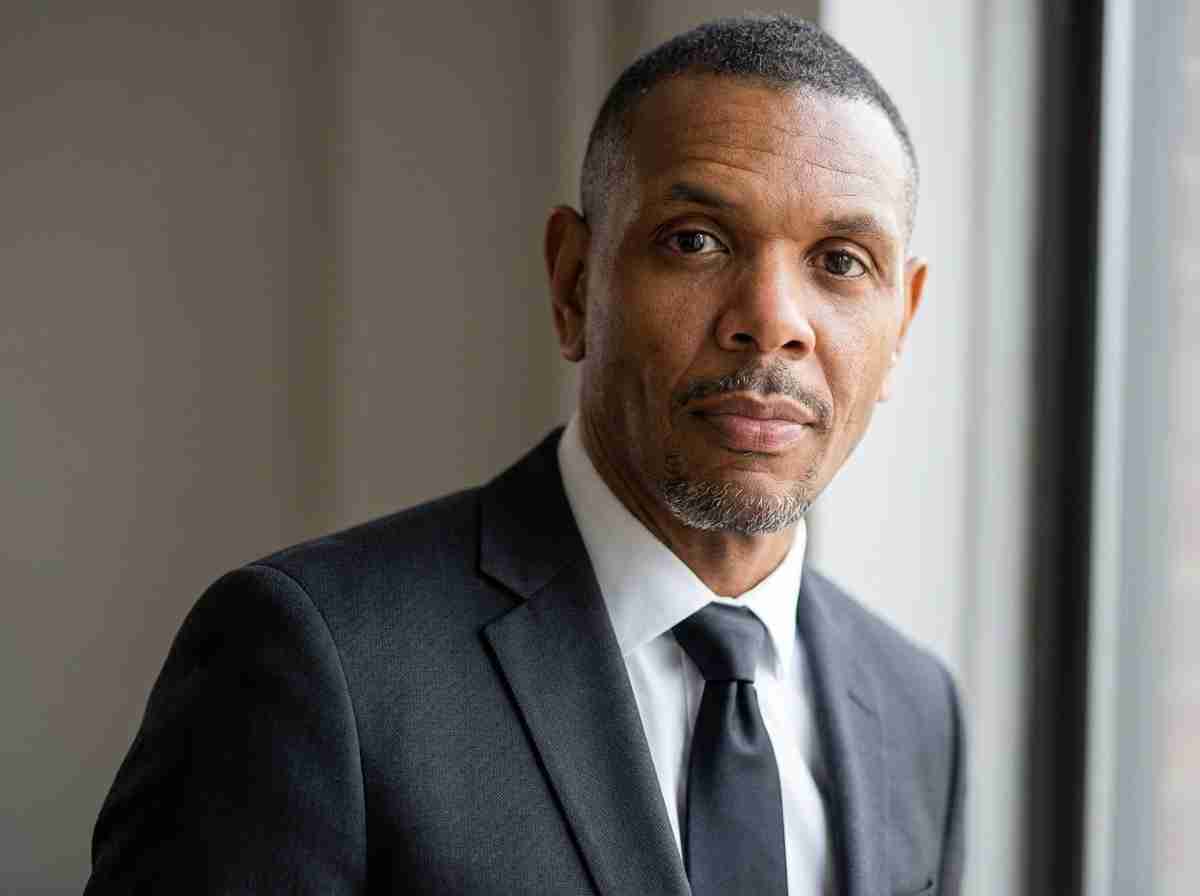
Your investor readiness programme will be led by Kurt Graver — Accountant, MBA, Founder of SGI Consultants — supported by a qualified team of specialists across financial modelling, pitch preparation, and investor targeting. Kurt personally oversees every investor readiness engagement and has 25 years of cross-sector business experience.
Investor Readiness Track Record
Startups Prepared for Investment
Average Valuation Improvement
Timeline Reduction
Funding Success Rate (vs 13% avg)
What Is Investor Readiness?
Investor readiness is the state of having every material, every metric, and every narrative that an investor will evaluate during a funding process prepared to institutional standard -- before the first meeting, not during the process.
The distinction matters because fundraising is a sales process with an unusual dynamic: you rarely get a second chance with the same investor. A VC who sees a weak financial model in a first meeting will typically not agree to a second meeting to review the improved version. A pitch that does not survive the partner discussion after your presentation will not be resurrected. The window to make the right impression is narrow, and the preparation that creates it needs to happen before you open that window, not while it is already open.
Most founders underestimate the depth of preparation that institutional investors expect. A pitch deck is a prerequisite, not a differentiator. What separates funded founders from unfunded ones at the serious investor stage is the completeness of the package behind the deck: the financial model that stands up to forensic analysis, the investment memorandum that answers questions before they are asked, the data room that signals professional competence, and the founder who can discuss churn cohorts and margin progression without reaching for their laptop.
We have prepared over 400 UK startups for this process. We know exactly what institutional investors are looking for at each stage, because we have watched the process from both sides of the table -- as the consultants preparing the materials and as the advisors in the room when those materials are evaluated.
For founders who are still in the concept or early traction stage and not yet ready for institutional investment, our startup consulting service provides early-stage support that leads into investor-readiness preparation when the time is right.
Who This Service Is For
Early-stage founders approaching their first institutional raise who have achieved early product-market fit signals and initial revenue, and are preparing to approach angels or seed-stage VCs for the first time. The gap between what founders think investors need and what investors actually evaluate is widest at this stage -- and the cost of getting it wrong is the loss of investor relationships that cannot easily be rebuilt.
Founders who have pitched and been declined and need an honest, expert assessment of why the materials or narrative failed. We work with a significant number of founders who have been through one or two unsuccessful fundraising attempts and need both a diagnosis and a rebuild. This is some of our most valuable work: identifying the specific weaknesses in an existing package and addressing them directly.
Pre-Series A startups preparing for a step up in investor calibre who have previously raised from angels or a small seed round and are now targeting institutional VCs for the first time. The expectations at Series A are materially different from seed stage -- in the depth of financial model, the rigour of the due diligence process, and the sophistication of the negotiation -- and the preparation required reflects those differences.
Corporate executives and technical founders entering the fundraising market for the first time who have deep domain expertise but limited experience of the UK investor landscape, the specific expectations of institutional investors, and the mechanics of term sheet negotiation. The fundraising process has conventions and dynamics that are not intuitive to founders who have not been through it -- understanding them is a material advantage.
University spin-outs and deep tech founders whose technology is genuinely differentiated but whose commercial narrative and financial model do not yet reflect the opportunity in terms that generalist investors can evaluate. Deep tech requires additional investor preparation around IP, technical risk, and regulatory pathway -- areas where standard pitch deck templates are inadequate.
The SGI Investor Readiness Methodology: 8 Phases
We view fundraising as a sales process that demands premium collateral. Over 10-16 weeks, we act as your interim CFO and Strategy Officer, systematically building every asset investors will evaluate during their diligence process.
Phase 1: Business Model Stress-Testing and Validation
Before we touch a pitch deck or financial model, we interrogate the business model. Investors will do this in the second meeting -- we do it first so you have defensible answers ready, rather than discovering weaknesses under pressure.
We analyse the unit economics in depth: Customer Acquisition Cost by channel, Lifetime Value by customer segment, Gross Margin relative to sector benchmarks, and Contribution Margin at different growth rates. If the unit economics do not work at any realistic scale, we address the model before presenting it to investors -- because a financial model built on broken unit economics is not a problem we can paper over with a good presentation. We have declined to work with founders whose economics were fundamentally unworkable, because the right outcome for them is to fix the model, not to prepare better materials for a raise that should not happen yet.
We also conduct competitive moat analysis at this stage. The questions "why you, why now, and why can't a competitor with ten times your resources replicate this in 18 months?" are not philosophical -- they are the questions a serious investor will ask in the second meeting. We prepare answers that are specific, defensible, and grounded in evidence rather than the founder's conviction about their own business.
Planetary Processing, the London deep tech company that completed a multi-source VC raise after our formation work, subsequently used our investor-readiness preparation for its Series A process. The business model validation phase identified a gap in how the IP licensing structure was presented to investors—it was technically correct but commercially unclear. Addressing this before the first investor meeting removed a question that would otherwise have been a consistent friction point throughout the process.
Phase 2: Institutional-Grade Financial Model
This is where most UK funding rounds fail before they begin. A simple revenue spreadsheet is not adequate for any investor beyond the most informal angel. A genuinely institutional-grade financial model is one that survives forensic analysis -- one that an investor's analyst can take apart line by line and find that every assumption is grounded and every projection is internally consistent.
We build fully integrated three-statement models -- Profit and Loss, Balance Sheet, and Cash Flow -- that are linked rather than independently constructed. An integrated model is the standard that experienced investors expect, because it ensures that growth assumptions in the P&L flow through correctly to cash consumption in the Cash Flow, and that the Balance Sheet balances under all scenarios. When these statements are not linked, it signals to an experienced investor that the financial model was produced by someone who does not fully understand the mechanics.
We model Base, Upside, and Downside scenarios. This is not an optional addition -- UK VCs specifically evaluate how founders think about downside scenarios. A founder who can only articulate the optimistic case is signalling that they have not seriously considered what happens when customer acquisition costs increase, when a key customer churns, or when the market develops more slowly than planned. The Downside scenario is where investor confidence is either built or lost.
We build the key metrics dashboard alongside the financial model: Monthly Recurring Revenue, Burn Rate, Runway, Annual Recurring Revenue growth rate, and the unit economics metrics by cohort. These are the numbers that will be referenced in every investor conversation from the first meeting to the closing, and they need to be both accurate and presented in the format investors expect.
Phase 3: Investor-Grade Pitch Deck
The pitch deck is produced after the financial model is complete -- not before. This sequencing matters because the pitch deck must make claims that the financial model supports. Building the deck first and the model second produces either a deck that overstates the financial picture or a model that is reverse-engineered to fit the deck. Neither survives due diligence.
We structure the narrative architecture of the deck around the psychological flow that moves an investor from scepticism to interest: Problem framing in economic terms, Solution with specific differentiation, Market sizing using the bottoms-up methodology from Phase 1, Traction evidence sequenced to show momentum, Team credentials presented as evidence of execution capability, and the Ask stated with the use of proceeds specific enough to be credible.
UK investors are particularly focused on the "why now" question -- the specific market, regulatory, or technological condition that makes this the right moment for this particular solution. We make this element of the narrative impossible to ignore because it is the question most founders answer inadequately in their early deck iterations.
We design for the room, not the PDF. A pitch deck that reads well on screen is not necessarily the same as one that works when the founder is presenting it live to a partner group. We account for the difference in how we structure each slide.
Phase 4: Investment Memorandum (The Deep Dive Document)
For serious investor conversations at the seed stage and above, a pitch deck alone is insufficient. The period between the first meeting and the term sheet is when the investor's analyst works through the business in detail—reviewing the claims in the deck, reading the financial model, and often preparing a detailed memo for the partner meeting. The Investment Memorandum is the document that shapes that analysis.
We produce a comprehensive 25 to 35-page memorandum that answers the questions an analyst will ask when the founder is not in the room. It covers the business model in full detail; the competitive landscape, with specific analysis of the most credible threats; the go-to-market strategy, including channel economics; the technical roadmap and IP considerations, where relevant; and the team, with specific evidence of relevant prior experience.
The Investment Memorandum is the document that distinguishes founders who are serious about institutional fundraising from those who are not. Most seed-stage founders do not have one. The ones who do stand apart in investor discussions, because the document signals the level of rigour that investors are committing their own capital to.
Phase 5: Due Diligence Preparation (The Question Bank)
The gap between a positive investor meeting and a signed term sheet is the due diligence process. This is where deals die -- not because the business is inadequate but because the founders cannot respond quickly, completely, and confidently to the questions the investor's legal and commercial teams raise.
We prepare a bank of written answers to over 100 anticipated due diligence questions covering business model, financial performance, competitive landscape, legal structure, intellectual property, regulatory compliance, team, and technical architecture. When an investor's analyst sends a due diligence request, founders who respond within 24 hours with comprehensive, well-referenced answers close deals faster and on better terms than founders who take two weeks to compile a partial response.
We also structure the data room before the fundraise begins. A well-organised data room -- with consistent naming conventions, a logical folder structure, and complete documentation -- signals professional competence at the moment the investor makes their final assessment. An incomplete or disorganised data room sends the opposite signal, and it sends it at the worst possible time.
We identify the specific characteristics of the business that are most likely to generate investor concern -- what investors might describe as "red flags" --, and we prepare the narrative to address them transparently. In our experience, founders who acknowledge genuine challenges and demonstrate they understand and are managing them build significantly more credibility than founders who attempt to minimise or conceal them. Investors who survive due diligence know what questions to ask. They prefer founders who have already asked those questions of themselves.
Phase 6: Valuation Guidance and Term Sheet Preparation
Entering a funding negotiation without an independent valuation framework is the single most common way UK founders give away unnecessary equity. The investor will always have a more sophisticated view of valuation mechanics than a first-time founder -- unless that founder has done the preparation.
We conduct a comparable company analysis using recent UK funding rounds and public market comparables in the relevant sector to establish a defensible valuation range. We use multiple valuation methodologies -- Revenue Multiples, Discounted Cash Flow, and market-based approaches -- to triangulate a range that can be defended against an investor's challenge.
We provide structured education on term sheet mechanics before the founder receives their first offer. Liquidation preferences, anti-dilution provisions, board composition, drag-along and tag-along rights, and information rights are all elements that a first-time founder can easily agree to without fully understanding their downstream implications. We ensure that when a term sheet arrives, the founder understands every clause and can negotiate from a position of knowledge rather than anxiety.
Phase 7: Investor Targeting & Outreach Strategy
Not all capital is equal. A strategic investor who brings relevant network connections, sector expertise, and introductions to future investors is worth significantly more than a passive cheque-writer at the same valuation. We ensure founders are pitching to the investors most likely to both write the cheque and add the most value to the business.
We build a curated target list of UK angels, VCs, and family offices relevant to the specific stage, sector, and geography—typically 30 to 50 targets for Comprehensive engagements. The curation reflects both fit and accessibility: we do not include investors on the list whose investment thesis does not clearly match the business, and we prioritise investors for whom the likelihood of a warm introduction is highest.
Where appropriate, we facilitate introductions through the SGI network. We maintain active relationships across the UK investment ecosystem -- relationships built over 12 years of working alongside founders who have gone on to become angels and VCs themselves, and through the track record of SGI-prepared companies that have raised funds from Atomico, Balderton Capital, Index Ventures, Octopus Ventures, and LocalGlobe.
We provide the outreach playbook: the initial email format, the follow-up sequence, and the timing strategy for managing a pipeline of 30 to 50 investors simultaneously. Fundraising is a full-time sales process, and the mechanics of running that process professionally -- maintaining momentum, creating competitive tension, and managing relationships without burning them -- are skills that can be taught.
Phase 8: Fundraising Timeline & Milestone Management
We manage the fundraising process as a project with clear milestones and explicit accountability, not as an open-ended exercise that either produces a term sheet or does not.
The week-by-week roadmap covers the full three- to six-month fundraising window: the initial outreach and first-meeting phase, the second-meeting and due diligence phase, the term-sheet negotiation phase, and the closing documentation phase. Each week has specific deliverables and review points that keep momentum alive during a process that has a well-documented tendency to lose momentum at exactly the wrong moment.
We provide a negotiation strategy for the term sheet phase, including how to create competitive tension when multiple investors are interested, how to evaluate the full economics of competing offers rather than focusing only on headline valuations, and how to manage investor relationships during the period between the term sheet and close. The closing phase -- managing legal documentation, final due diligence, and the mechanics of getting the money into the bank account -- is handled with the same rigour as the preparation phase.
Who Funds Our Clients
We maintain working relationships across the full UK capital stack. Our track record with institutional investors is one of the strongest trust signals we can offer -- because it is verifiable, specific, and reflects outcomes rather than intentions.
Venture Capital. Our clients have raised funding from Tier-1 UK VC firms, including Atomico, Balderton Capital, Index Ventures, Octopus Ventures, and LocalGlobe. These are competitive, rigorous processes in which the expected standard of preparation is high. The fact that SGI-prepared founders have successfully raised funds from these firms is the most direct evidence of the quality of our preparation work.
Angel Networks and Syndicates. We prepare founders to pitch effectively to leading UK angel networks, including SFC Capital, the Oxford Investment Opportunity Network (OION), and Cambridge Angels. Seed-stage angel investment requires different preparation from VC -- the relationship dynamics, the depth of due diligence, and the decision-making process are all different, and we calibrate our preparation accordingly.
Non-Dilutive Funding. Beyond equity, we help founders identify and secure non-dilutive capital from Innovate UK Smart Grants, regional development funds, and sector-specific grant programmes. For businesses in technology, life sciences, clean energy, or advanced manufacturing, non-dilutive funding can significantly extend runway before pricing an equity round—typically allowing founders to demonstrate more traction before raising, resulting in better terms.
Sign Up & Get Your Book Your Free Funding Route Call
Investment Readiness Pricing
Preparation work is charged as a fixed fee, quoted before it starts, so you know what you are paying before you commit. Where we go on to run the raise itself, that is handled separately on a success-fee basis, so we are paid when you are funded rather than for the attempt.
From
Readiness Assessment
Where every engagement starts. 100 points across nine weighted components, an adversarial screen of your deck, website, and founder profiles against the checks an investor's own first-pass screening applies, and a named list of every gap and how to fix it.
Scored twice: as you are today and as you could be. Yours, whether or not you raise.
From
Essential
- Business model validation
- Investment summary
- Three-statement financial model
- Investor-grade pitch deck (12-15 slides)
- Valuation guidance (comparables)
- 30 days post-delivery support
Suited to pre-seed and seed rounds, £250K to £1M
From
Comprehensive
- Everything in Essential, plus:
- Investment memorandum (25-35 pages)
- 100-question due diligence bank
- Data room organisation
- Investor database (30-50 graded targets)
- Email outreach templates
- 60 days post-delivery support
Suited to seed and Series A rounds, £1M to £4M
Premium
- Everything in Comprehensive, plus:
- Advanced scenario modelling with sensitivity analysis
- Bespoke investor documentation suite
- Premium pitch deck with custom design
- Full data room preparation
- 90-day advisory access
Suited to Series A and above, or complex structures
Why Choose SGI Over Alternatives?
Factor | Freelance Pitch Designer | Investment Bank | SGI Consultants |
Investment | £2,000-£5,000 | £50,000+ retainer + 3-5% success fee | £900 - £2500 fixed |
Financial Modelling | Basic revenue forecast | Sophisticated but expensive | Institutional-grade, practical |
Due Diligence Prep | Not included | Comprehensive but overkill | Exactly what early-stage needs |
UK Market Focus | Generic templates | London-centric | Entire UK startup ecosystem |
Investor Access | None | Extensive but expensive | Graded investor targeting, facilitation on success-fee terms |
Stage Expertise | Pre-seed only | Series B+ | Pre-seed through Series A |
Delivery Timeline | 2-3 weeks (deck only) | 3-6 months | 6 weeks (Intensive) or 3 to 4 weeks (documentation) |
The brutal truth: freelancers give you slides, investment banks are built for £10M+ rounds, and most consultants have never actually raised capital themselves. I've personally helped over 600 UK startups through this process—this is what we do.
Explore Further
Related reading:
- Mastering Series A Fundraising: Your Complete Guide — What Series A investors expect and how to prepare
- Startup Valuation Methods That Ensure Success — How to value your business before approaching investors
- Pre-Seed & Seed Funding Explained Clearly — Understanding the funding stage landscape before beginning your raise
Free resource:
- The Complete Funding & Investor Toolkit → — Pitch deck templates, investor outreach scripts and due diligence checklists
Content hub:
- Business Funding & Finance Hub → — Complete equity funding guides for UK startups
Related services:
- Investor-Ready Business Plans — The core documentation produced during the programme
- Business Model Development — Strengthen your revenue model before approaching investors
- Business Funding Service — We facilitate investor introductions after the programme
Investor Readiness Track Record
We have prepared over 400 startups for institutional investment, helping clients secure over £250 million in total funding. Our methodology consistently delivers a 73% funding success rate—drastically outperforming the industry average of ~13% for self-managed raises.
Our investment preparation has enabled clients ranging from Cambridge University spin-outs securing deep-tech capital to high-growth SaaS platforms closing oversubscribed Series A rounds.
What Makes SGI Different
The UK market for investor-preparation support lies between two inadequate options. Freelance pitch designers produce slides—typically in two to three weeks —without touching the financial model, due diligence preparation, or investor targeting. Investment banks produce comprehensive work, but their minimum engagement sizes and success-fee structures are designed for transactions above £10 million, making them inaccessible and economically irrational for founders from pre-seed through Series A.
We occupy the space between these options: institutional-grade preparation delivered on timelines and with fee structures appropriate to early-stage fundraising. Our three-statement financial models are built to the same standard as those produced by an investment bank. Our investment memoranda are the documents that pass partner meetings at Tier-1 VCs. Our due diligence banks are built from the actual questions that institutional investors ask in the UK market.
The additional differentiator is our track record with active UK investors. An introduction from SGI to an investor who has already seen SGI-prepared founders complete successful raises is a different conversation from cold outreach. We have built those relationships across Kurt's 25-year career and more than 400 investor readiness engagements
For founders whose businesses need a business plan alongside investor preparation—which is common for founders approaching debt funding or grant applications concurrently with equity—we coordinate the two deliverables to ensure the financial model and narrative are consistent across both documents. For founders who have already completed their startup formation and concept validation with us, the investor readiness engagement builds directly on that work rather than starting from scratch.
Our business consulting service provides post-investment growth support for founders who have closed a round and need structured help deploying capital effectively.
Explore detailed examples of how our business services have enabled clients to secure funding and achieve growth:
Stop Pitching. Start Closing.
Every day you spend fundraising with inadequate materials is a day you're not building your business. It's a day of runway consumed. And it's a day when you risk burning bridges with UK investors who give you only one shot.
You have the vision. You have the team. You have the product. Don't let poor preparation be the reason you hear "no."
Partner with SGI to build the institutional-grade fundamentals that give investors the confidence to write the cheque.
Frequently Asked Questions (FAQs)
Our investor readiness engagements run 10 to 16 weeks from kickoff to completion of materials. Essential Preparation typically completes in eight to ten weeks. Comprehensive and Premium engagements, which include the Investment Memorandum and due diligence bank, run for 12 to 16 weeks. We do not compress these timelines at a founder's request -- the preparation requires the time it needs, and a pitch deck produced in two weeks without the financial model and due diligence preparation behind it is not investor-ready. It is a slide deck.
No ethical consultant can guarantee funding—investor decisions depend on market conditions, timing, and your execution. However, our 73% success rate (vs. the 13% UK industry average) demonstrates that proper preparation dramatically improves your odds. If we assess during our initial scoping that your business isn't fundable yet, we'll tell you honestly and recommend building more traction first. We've turned down clients who weren't ready because taking their money when they'd fail anyway is unethical.
Yes. We facilitate warm introductions to relevant Angels, VCs, and Family Offices in our network where an appropriate fit exists. I've personally placed clients with Atomico, Balderton Capital, and Index Ventures, among others. However, I'm not a broker-dealer, and introductions are most valuable when your materials are institutional-grade. I lead with quality preparation, then leverage the network strategically.
Preparation is a fixed fee, paid upfront or in instalments. Facilitation, meaning running the raise itself, carries a £299 setup fee, plus a success fee payable upon completion, under our 18-month no-win, no-fee guarantee. The two are separate: you can take preparation without facilitation, and the £299 is credited against any preparation you buy. We do not take equity in client businesses.
That's exactly what Phase 6 addresses. I conduct a comprehensive comparable company analysis, reviewing recent UK funding rounds for similar businesses and relevant public comparables. I build valuation scenarios using multiple methodologies (Revenue Multiples, DCF, market-based) to give you a realistic range based on your stage and traction. You won't underprice your equity or price yourself out of the market.
Our Investor Readiness service is designed primarily for institutional capital (Angels, VCs, Family Offices), which requires the highest level of sophistication. However, the assets we create—financial model, pitch deck, business case—are also critical for successful equity crowdfunding campaigns. The pitch strategy differs, but the fundamentals remain identical. If you're raising on Seedrs or Crowdcube, this preparation is essential
Very. This is a collaborative process, not outsourced work. I need weekly working sessions with you and your founding team—typically 2-3 hours per week for 10-16 weeks. You bring the product knowledge and vision; I get the methodology and investor lens. The most successful engagements are when founders are fully committed to the process and available for rapid iteration.
For angel and pre-seed investment, meaningful traction is helpful but not always required -- particularly for technical founders with strong prior experience or a clearly differentiated technology. For seed-stage institutional VCs, some evidence of product-market fit is typically expected, such as paying customers, meaningful user engagement, or strong LOIs from prospective customers. For Series A, the expectations are significantly higher: consistent revenue growth, improving unit economics, and a clear hypothesis for how the raised capital accelerates a business that is already working. We assess where each founder sits relative to these thresholds as part of the free initial assessment.
A pitch deck is a presentation document -- typically 12 to 15 slides -- designed to be presented live by a founder and to prompt investor interest and a second meeting. An Investment Memorandum is a written document of 25 to 35 pages designed to be read by an investor's analyst or partner without the founder present, and to provide the level of detail required to make a funding decision. The pitch deck creates interest. The Investment Memorandum provides the evidence base that converts interest into a term sheet. Both are required for any serious rise above pre-seed level.
Yes -- and this is a meaningful proportion of our work. Founders who have pitched unsuccessfully typically have one or more of the following four problems: a weak financial model, an unclear or undifferentiated narrative, misaligned investor targeting (pitching to investors whose thesis does not match), or inadequate due diligence preparation. We conduct a diagnostic assessment to determine what went wrong and rebuild the materials to address those weaknesses. This is not a cosmetic refresh -- it is a structured rebuild based on evidence of why the previous process failed.
We maintain working relationships across the UK investment ecosystem and, where appropriate, facilitate warm introductions for clients on the Comprehensive and Premium tiers. We do not guarantee introductions to specific firms -- investment relationships are built on the quality of the business and the preparation, not on the intermediary. What we can do is ensure that, when an introduction is made, the business is presented in the best possible light and that the supporting materials are strong enough to hold investors' attention.
We work across pre-seed through Series A. Our Essential Preparation tier is calibrated to pre-seed and angel rounds of £250,000 to £1 million. Comprehensive Preparation serves seed rounds of £1 million to £4 million. Premium Preparation with Placement Support is designed for Series A rounds of £4 million and above. For raises beyond Series A, the preparation requirements typically involve investment banking capabilities that we would coordinate alongside our advisory work rather than replace.
The industry average for founder-managed fundraising processes is approximately 13% -- meaning roughly one in eight founders who approach institutional investors without professional preparation secure funding. Our 73% success rate across investor-readiness engagements reflects both the quality of our preparation and the selectivity of our client intake: when a business model is fundamentally unworkable, we advise founders against proceeding with a fundraise rather than preparing materials for a raise that should not happen. Both factors contribute to the outcome rate.
Important information on our regulatory status
SGI Consultants Ltd is not authorised or regulated by the Financial Conduct Authority. We are a business advisory and funding facilitation consultancy. We do not lend, act as a credit broker, or provide regulated financial advice or personal investment recommendations.
Our work is the preparation, presentation and coordination of funding applications and investor processes. Where an element of an engagement requires FCA authorisation, we work alongside FCA-authorised partners who carry out that regulated activity, and we will make this clear to you when it applies.
Nothing on this page is an offer, an inducement or an invitation to engage in investment activity, and nothing here constitutes financial, legal or tax advice. You should take independent professional advice before entering into any funding arrangement.