
Specialist Business Plans UK - CQC, Ofsted, FCA, OISC
A standard business plan focuses on optimism. A regulator focuses on risk. The same document cannot satisfy both. We produce regulatory business plans that satisfy CQC, Ofsted, FCA, OISC, and commercial landlord assessment frameworks, built around the specific evidence and stress-testing that gatekeepers actually evaluate.
Most generalist business plan writers fail in this arena because they apply a funding-first approach: aggressive growth, blue-sky market potential, optimistic revenue forecasts. To a CQC inspector or FCA caseworker, optimism reads as risk. To a commercial landlord assessing a 10-year lease commitment, aggressive projections read as instability. Regulators do not accept assertions; they require evidence: safeguarding policies, capital adequacy calculations, stress-tested resilience, and operational frameworks that demonstrate sustainable compliance from day one.
We have prepared regulatory plans for UK applicants since 2014, working with healthcare and social care operators, education and childcare providers, financial services firms, immigration advisers, and commercial tenants across hospitality, retail, and industrial property. Plans are formatted to each regulator's specific framework and built around the assessment criteria that the relevant inspector or caseworker will apply.
Book a free 30-minute Specialist Planning Consultation. We will identify your specific regulatory body, assess your current readiness, and map out the exact evidence required to maximise the probability of approval. No obligation.
Who Delivers This Service
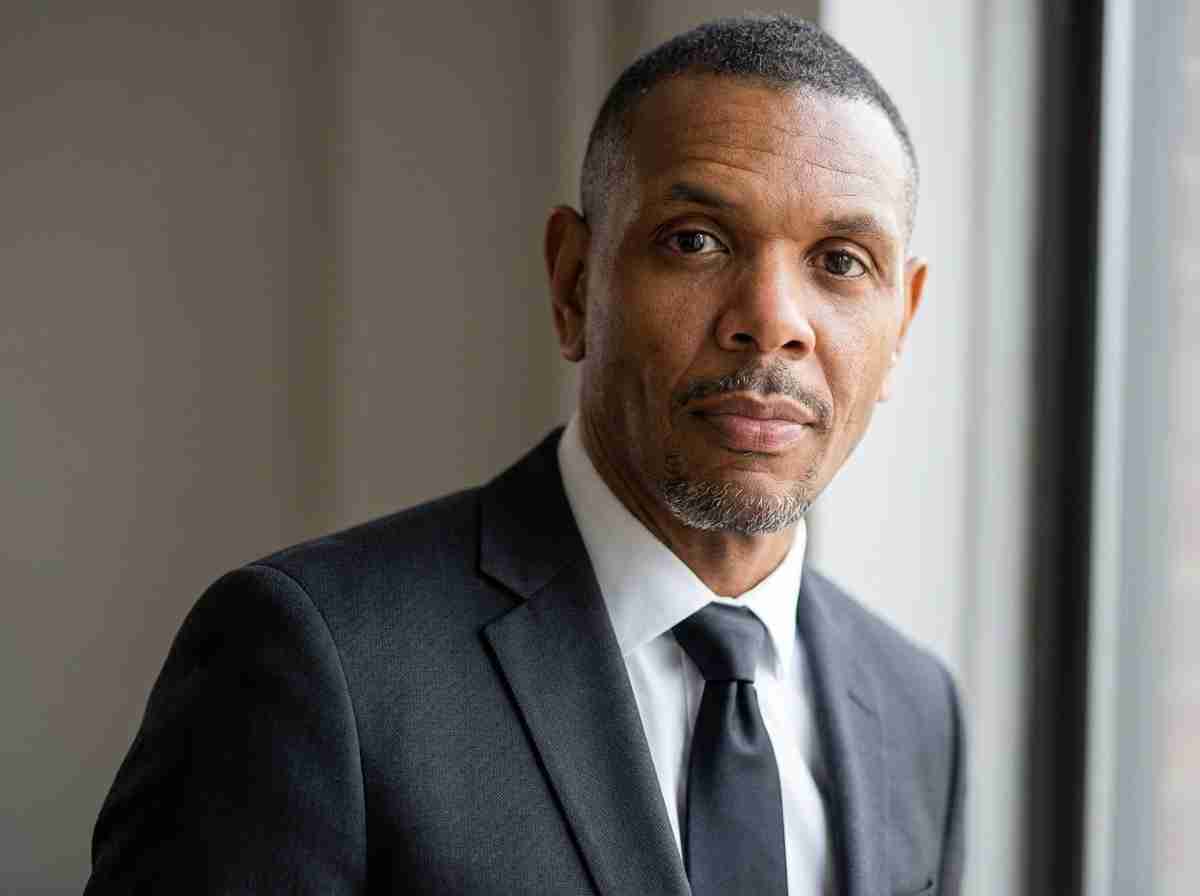
Your specialist business plan will be led by Kurt Graver — Accountant, MBA, Founder of SGI Consultants — supported by a qualified consulting team with experience across 47+ industries. Kurt personally oversees every specialist engagement, bringing the cross-sector pattern recognition that complex business models require.
Specialised Success in High-Compliance Sectors
We don't guess at the criteria. We rely on a database of over 300 successful specialist applications to know exactly what the assessor is looking for.
Approval Rate Across All Regulatory Bodies
Specialist & Regulatory Plans Delivered
of Experience in Niche Compliance Planning
10+
Approvals From Different Regulatory Bodies
Why Regulatory Business Plans Get Rejected — And How We Address Each Cause
The three most consistent reasons regulatory business plans are rejected are not failures of the underlying business — they are failures of documentation. Assessors across the CQC, Ofsted, and FCA see the same mistakes repeatedly, and they have less tolerance than commercial investors for plans that do not demonstrate specific operational competence.
Failing financial sustainability tests. Regulatory bodies — particularly the CQC and FCA — require demonstration that the business can maintain service quality and financial stability even under adverse conditions. A CQC application that shows a care home at full occupancy from Month 1 with no contingency for below-capacity operation will be challenged immediately. An FCA application that cannot model Capital Adequacy under stressed market conditions will fail the Threshold Conditions assessment. We build Regulatory-First financial models: conservative, scenario-tested projections that prove sustainability without relying on optimistic assumptions. Every financial assumption is documented and defensible.
Inadequate policy framework integration. Regulators do not accept references to policies that will be developed later. A CQC application must demonstrate that safeguarding policies, staffing matrices, medication management procedures, and Fit and Proper Person processes are already designed and ready for implementation. An Ofsted application must demonstrate EYFS compliance, key person systems, and safeguarding frameworks in place from Day 1. We integrate the specific policy structures required by each regulatory body into the business plan itself — not as appendices, but as core sections of the compliance narrative.
Generic rather than body-specific documentation. The CQC's Key Lines of Enquiry (KLOEs) — Safe, Effective, Caring, Responsive, Well-led — are specific assessment criteria that require specific responses. An application that addresses them generically or does not use the CQC's own vocabulary signals to the assessor that the applicant does not fully understand what they are registering for. The FCA's Consumer Duty requirements, the SM&CR Senior Managers framework, and Ofsted's Early Years Foundation Stage ratios are not interchangeable — each requires documentation written in that regulator's language. We produce documentation that speaks directly to the assessor.
Who We Work With
Regulatory business plan applicants come to us under time pressure with high stakes. A rejected CQC application delays a care home launch by months and triggers a formal record with the regulator. An FCA authorisation refusal is a significant setback for a financial services business. The applicants we support most frequently are:
Care homes, domiciliary care, and supported living providers are registering with the CQC. You are opening a new regulated activity — a residential care home, a home care service, or a supported living provision — and need to demonstrate to the CQC that your service will be Safe, Effective, Caring, Responsive, and Well-led from the outset. The registered manager's credentials, staffing ratios, safeguarding policies, and financial sustainability all need to be addressed specifically and evidentially. We have an 89% first-application approval rate on CQC registrations.
Dental practices, GP surgeries, and independent healthcare providers registering regulated activities. Healthcare practices registering with the CQC for the first time — or adding new regulated activities to an existing registration — face a Fit and Proper Person assessment of the nominated individual and Registered Manager, alongside the standard service assessment. We understand how the CQC treats healthcare practice ownership structures and what evidence of clinical governance the application requires.
Nurseries, childminders, and independent schools registering with Ofsted. Early years providers must demonstrate compliance with the Early Years Foundation Stage framework from the point of registration — including key-person systems, safeguarding arrangements, staff qualification requirements, and child-to-staff ratios. We align the business plan precisely with the EYFS statutory framework and the specific requirements of the Ofsted registration process. Our early years registration approval rate is 92%.
Financial services firms applying for FCA authorisation. Investment advisers, consumer credit firms, payment service providers, and e-money institutions face the most demanding regulatory documentation process in the UK. The FCA's Threshold Conditions — Legal Status, Location of Offices, Appropriate Resources (including Capital Adequacy), Suitability, and Business Model — each require a substantive response supported by financial models, systems documentation, and a Consumer Duty framework.
Immigration advice firms seeking OISC registration at Level 2 or 3. OISC registration at the higher levels requires demonstrated competence, adherence to ethical practice standards, client care documentation, CPD frameworks, and professional indemnity insurance at an adequate level. We produce the operational and financial documentation that sits alongside the competence assessments required by the OISC. Our OISC registration approval rate is 88%.
Businesses are securing commercial leases from institutional landlords. A commercial landlord — particularly for restaurant, retail, or industrial units in prime locations — conducts due diligence on prospective tenants that is more rigorous than that required for many funding applications. They need evidence of rent affordability, personal financial standing, fit-out funding, and business viability over the lease term. We produce business plans that function as a 'CV for the business' — demonstrating low tenancy risk through conservative cash flow forecasting and documented personal and business financial strength.
Law firms and compliance consultants require specialist business planning support. We work as a documentation subcontractor for law firms, including Mishcon de Reya, Paragon Law, and Duncan Lewis Solicitors, producing regulatory business plans that integrate with our legal partners' overall client strategies. We accept briefs directly from legal teams and coordinate with them throughout the process rather than requiring the client to manage communication between advisers.
Sector-Specific Compliance Business Plans
Each regulatory body applies a different assessment framework with different evidence standards, financial tests, and documentation requirements. Using a generic structure across regulatory contexts is one of the most reliable ways to produce documentation that satisfies none of them well. We build each plan around the body's specific assessment criteria.
1. CQC Business Plans — Health & Social Care Registration
89% first-application approval rate
The Objective: Registration for care homes, domiciliary care services, supported living, dental practices, GP surgeries, and independent healthcare providers.
The SGI Approach: The CQC assesses applications against the Key Lines of Enquiry (KLOEs): Is the service Safe, Effective, Caring, Responsive, and Well-led? Financial viability is assessed separately to determine whether the service has the resources to maintain quality without compromising safety, including through periods of below-maximum occupancy. We explicitly build the business plan around these criteria, using the CQC's own language and evidence standards, and integrate safeguarding policies, Fit and Proper Person documentation, staffing qualification matrices, and a Registered Manager profile directly into the compliance narrative.
Key components: KLOE-structured compliance narrative, staffing plans with qualification matrices and rota modelling, safeguarding policy integration, conservative financial sustainability model with occupancy sensitivity analysis, Fit and Proper Person statement, Nominated Individual documentation.
Ideal for: residential care homes, nursing homes, domiciliary care services, supported living providers, dental practices, GP surgeries, and independent hospitals.
2. Ofsted Business Plans — Early Years & Education Registration
92% early years registration approval rate
The Objective: Registration for day nurseries, pre-schools, childminders, children's homes, and independent schools.
The SGI Approach: Ofsted's registration process for early years providers centres on the Early Years Foundation Stage statutory framework — specifically, whether the provider has the staff qualifications, ratios, safeguarding arrangements, and curriculum implementation approach to meet EYFS requirements from Day 1 of operation. We align every element of the business plan with the EYFS statutory framework, demonstrate that staffing meets ratio requirements at different occupancy levels, and integrate health and safety risk assessments appropriate to the setting. Financial modelling is built on occupancy-based revenue stress testing to demonstrate viability at below-capacity operation.
Key components: EYFS curriculum implementation framework, staff qualification and ratio analysis, safeguarding and child protection policy integration, key-person system documentation, occupancy-based financial stress testing, and premises suitability evidence.
Ideal for: day nurseries, pre-schools, childminders, wrap-around care providers, children's homes, and independent schools.
3. FCA Business Plans — Financial Services Authorisation
78% approval rate
The Objective: Authorisation for investment firms, consumer credit businesses, payment service providers, and e-money institutions.
The SGI Approach: FCA authorisation is among the most demanding regulatory documentation processes in the UK commercial landscape. The FCA's Threshold Conditions require a response across five dimensions: Legal Status, Location of Offices, Appropriate Resources (including Capital Adequacy and Liquid Asset Buffer requirements), Suitability (the Fit and Proper Person assessment for senior managers under SM&CR), and Business Model viability. We build sophisticated Capital Adequacy models to prove that the required financial resources are maintained under stressed market conditions, and we produce the Systems and Controls documentation, Consumer Duty risk framework, and SM&CR Senior Managers arrangements that the FCA expects to see in a complete application.
Key components: Threshold Conditions response document, Capital Adequacy model with stress scenarios, Liquid Asset Buffer calculation, Consumer Duty risk framework, SM&CR Senior Managers and Certified Persons arrangements, systems and controls documentation, wind-down plan.
Ideal for: investment advisers (MiFID and non-MiFID), consumer credit firms, payment institutions, e-money institutions, and mortgage intermediaries.
4. OISC Business Plans — Immigration Advice Registration
88% registration approval rate
The Objective: Registration at Level 2 or Level 3 for immigration advice organisations and individual advisers.
The SGI Approach: The OISC assesses both the competence of individual advisers and the operational fitness of the organisation. Level 2 and 3 registrations require documentation of fee structures and client care arrangements, professional indemnity insurance at appropriate coverage levels, CPD planning and ongoing competence maintenance, complaint-handling procedures, and the financial sustainability of the practice. We document all of these elements in the business plan, alongside financial projections that demonstrate the practice can operate sustainably at the proposed fee levels and client volumes.
Key components: fee structure and client-care letter frameworks, professional indemnity insurance adequacy analysis, CPD planning and competence monitoring, complaint-handling procedures, client-account management protocols, and financial sustainability model.
Ideal for: immigration advice organisations, solicitors expanding into immigration services, and newly qualified advisers seeking Level 2 or 3 registration.
5. Commercial Landlord Business Plans — Lease Applications
Securing commercial premises in competitive locations
The Objective: Securing leases for restaurants, retail units, office space, and industrial premises from institutional and private landlords.
The SGI Approach: Commercial landlords — particularly in prime retail and hospitality locations — conduct prospective-tenant due diligence as rigorous as a bank lending assessment. They are evaluating rent affordability, business viability over the lease term, fit-out funding, and the principals' personal financial standing. We produce documentation that serves as a comprehensive 'CV for the business': conservative cash flow forecasts demonstrating rent cover under realistic trading assumptions, personal financial statements, fit-out budget verification, and a trading history or pre-opening plan that reduces the landlord's perception of vacancy and default risk.
Key components: conservative cash flow forecasts with rent-cover analysis, personal financial statements, fit-out budget and funding verification, trading history or pre-opening trading plan, market analysis specific to the premises' location, operator credentials and sector experience.
Ideal for: restaurant and hospitality operators, retail businesses, professional service firms seeking office space, and businesses requiring industrial or warehouse premises.
6. Other Specialist Regulatory Plans
Beyond the five core sectors above, we produce specialist business plan documentation for a range of other licensing and regulatory contexts, including:
Gambling Commission applications. Personal Management Licences and Operating Licences require documentation of the source of funds, business model sustainability, responsible gambling procedures, and anti-money laundering frameworks. We produce the compliance documentation that sits alongside the formal application.
Food Standards Agency and Local Authority licensing. Food manufacturing businesses, licensed premises, and businesses operating under Local Authority licensing schemes (alcohol, entertainment, late night refreshment) require business plans that demonstrate regulatory awareness and compliance-first operations.
Companies House and Companies Registration. Overseas businesses establishing UK subsidiaries often require comprehensive business plans for Companies House filings, opening bank accounts, and engaging professional services. We produce UK-standard documentation that serves multiple purposes across the registration process.
Book A Strategic Assessment and Business Plan Evaluation
Specialist Business Plan Pricing
Specialist business plans vary wildly in scope. A street trading licence is not the same as a banking licence. Our pricing reflects the regulatory burden, the depth of evidence required, and the volume of policy documentation we need to integrate.
We offer fixed-fee transparency. You'll know exactly what the investment is before we begin.
From
Basic Regulatory Plan
- Core regulatory business plan
- Basic compliance framework
- 3-year financial projections
- Policy template integration
- Regulatory body-specific formatting
- 10-14 days delivery
From
Standard Regulatory Plan
- Comprehensive regulatory plan
- Detailed compliance documentation
- 5-year financial model with stress testing
- Policy coordination and integration
- Evidence compilation support
- Regulatory advisor liaison
- 14-21 days delivery
Premium Regulatory Plan
- Institutional-grade regulatory documentation
- Advanced compliance frameworks
- Multi-scenario financial modelling
- Complete policy manual development
- Professional advisor coordination
- Application form completion
- Priority processing
- 14-21 days delivery
Complex Licensing (FCA/Banking)
- Bespoke high-stakes regulatory applications
- Systems and controls documentation
- Capital adequacy modelling
- Consumer Duty frameworks
- Ongoing regulatory support
- Application portal management
What's Included in Your Business Plan Package
All Specialist Business Plans Include | Standard & Premium Also Include | Premium Only Includes |
|
|
|
Explore Further
Related reading:
- Business Plans: Insights from 500 Evaluated Cases — Why complex businesses need specialist documentation
- 5 Business Strategic Models That Transform Decision Making — Strategic frameworks that underpin complex business plans
- Competitive Analysis for Business Plans (Complete Guide) — Building the market analysis section for unique business models
Free resource:
- The Business Plan Template Masterpack → — Adaptable templates for complex and multi-stream business models
Content hub:
- Business Planning & Strategy Hub → — Resources for building credible business documentation
Related services:
- Business Plan Writers — Full overview of all business plan services
- Investor-Ready Business Plans — For specialist businesses seeking equity investment
- Strategic Business Planning Service — Operational planning for complex and scaling businesses
Specialist Business Plans That Secure Registration and Approval
Why SGI — Not a Sector Consultant, Not a Generic Plan Writer
Sector-specialist consultants — healthcare management consultants, FCA compliance advisers, childcare specialists — understand their regulatory framework in depth but rarely produce the level of financial modelling and strategic business documentation that a complex regulatory application requires. They advise on compliance; they do not build business plans.
Generic business plan writers produce commercially formatted documents that are well-structured but not compliance-tested. They are not familiar with what a CQC assessor looks for in a staffing matrix, what an FCA analyst needs to see in a Capital Adequacy model, or what an Ofsted inspector considers adequate evidence of EYFS curriculum implementation.
SGI Consultants occupies the intersection. We understand the compliance frameworks because we have built documentation for each of the bodies listed on this page— repeatedly over 12 years, across different sectors and business scales. We understand the financial modelling requirements because we apply the same institutional-grade approach we use for commercial lending and investor documentation. And we work alongside sector specialists and regulatory solicitors as a documentation subcontractor, meaning our plans support the legal and compliance case your advisers are building rather than creating inconsistencies within your overall application.
We have delivered over 300 specialist regulatory business plans across the UK's principal compliance sectors, maintaining an overall approval rate of 87% or above. The cases below represent a cross-section of regulatory contexts and client situations.
Named Outcomes Across Regulatory Sectors
CQC registration — residential care home, South London: A healthcare entrepreneur opening a 24-bed residential care home in South London engaged SGI after an initial CQC pre-registration meeting, which identified gaps in the financial sustainability model and the staffing qualification matrix. We rebuilt the financial model around a conservative occupancy ramp-up from 40% in Month 1 to 85% by Month 9, demonstrated rent coverage and staffing-cost affordability at each occupancy level, and produced a detailed qualification matrix for all 14 proposed care staff roles. The registration was approved on first formal submission following the pre-registration meeting.
Ofsted registration — day nursery, 40-place urban setting: A nursery operator applying to register a 40-place day nursery in a converted commercial property needed documentation that demonstrated EYFS compliance from opening day. The challenge was proving that staff ratios would be maintained across different room configurations as occupancy grew. We built a room-by-room occupancy and staffing model, integrated the EYFS ratio requirements into the financial projections, and produced the safeguarding framework and key-person system documentation required for registration. Ofsted approved the registration within the standard processing timeline.
FCA authorisation — consumer credit firm: A consumer credit business seeking FCA authorisation for a peer-to-peer lending platform engaged SGI to prepare the full authorisation documentation package. The FCA's Appropriate Resources assessment required a Capital Adequacy model demonstrating that the firm held sufficient regulatory capital under stressed market conditions — a requirement that the founders had not anticipated when approaching the application. We built a Capital Adequacy model calibrated to the firm's expected loan book profile, produced the Consumer Duty framework and SM&CR arrangements, and prepared the systems and controls documentation. The firm received conditional authorisation within the standard FCA processing timeframe.
Commercial lease — restaurant premises, prime London location: A restaurant group seeking to take on a further central London premises required documentation that satisfied the institutional landlord's tenancy due diligence. The group had strong existing trading results, but the landlord required evidence of site-specific viability for the new location — a different trading demographic and competitive environment from the group's existing sites. We built a location-specific financial model using footfall data and competitor analysis for the target area, produced a personal financial statement for the director-guarantor, and prepared a fit-out plan and funding verification. The lease was signed within three weeks of submission.
Further outcomes available across: NHS and private healthcare | Independent education | Financial services and FinTech | Childcare and early years | Professional and legal services | Hospitality and licensed premises
Don't Let Compliance Block Your Launch
A rejected regulatory application is not simply an administrative setback. It creates a record with the regulator, can trigger formal scrutiny of future applications, and delays the revenue your business was planned around. The cost of comprehensive professional documentation is a fraction of the cost of refusal, resubmission, and delayed launch.
Schedule a Free Compliance Readiness Assessment today. In this 45-minute consultation, we will identify your specific regulatory body and application type, assess your current documentation and evidence readiness, map the specific evidence you need to secure approval, and give you an honest view of any gaps before you invest in the application process.
We will tell you if your business is not yet ready for the regulatory process, because documentation that does not meet the assessment criteria will be refused, regardless of how well it is written.
Frequently Asked Questions (FAQs)
No professional can guarantee regulatory approval, because decisions depend on factors beyond the business plan — including the applicant's personal character, criminal record checks (DBS for health and childcare, FCA fitness and propriety assessments), the suitability of the premises, and the regulatory body's current processing approach.
We can guarantee that your business documentation will meet the compliance standards of the relevant regulatory framework. Our approval rates — 92% for Ofsted early years, 89% for CQC first applications, 88% for OISC, 78% for FCA (all well above average) — reflect the standard of documentation we produce. Where applications are refused, the grounds for refusal are rarely the business plan itself, and when they are, we provide a complimentary revision.
Yes — a significant proportion of our work involves supporting resubmissions after an initial rejection. The first step is a detailed review of the refusal letter, which will specify the exact grounds for rejection. Regulatory refusals are typically very specific: inadequate evidence for a particular KLOE, a gap in the Capital Adequacy model, an incomplete policy framework, or insufficient evidence of financial sustainability.
We analyse the refusal, identify the specific deficiencies, and rebuild the relevant sections of the documentation to address them directly. We do not simply resubmit the same plan with cosmetic changes — we produce a substantively improved response to the regulatory body's stated concerns.
We provide policy templates and compliance frameworks within the business plan to demonstrate that the applicant has appropriate policies in place and ready for implementation. This is the standard required by most regulatory bodies at the application stage.
For organisations requiring comprehensive operational policy manuals — a full CQC compliance handbook, an Ofsted safeguarding policy suite, or an FCA policy and procedures manual — we offer additional policy development services beyond the business plan itself. The scope and pricing for this work is discussed and agreed at the initial consultation.
For a Standard regulatory plan — CQC, Ofsted, or commercial landlord — the typical timeline is 14–21 business days from the start of engagement to a complete first draft. Basic plans for straightforward registrations are 10–14 days. Premium plans are prioritised for 14–21 days.
FCA and complex banking licence applications take a minimum of 21–30 days due to the volume of technical documentation required — Capital Adequacy modelling, Consumer Duty frameworks, SM&CR arrangements, and systems documentation cannot be compressed without compromising quality.
An Express service (48–72 hours for a first draft) is available on Basic and Standard tiers. Express delivery requires complete information to be provided at the start of the engagement — we cannot meet urgent deadlines if supporting information is provided incrementally.
Standard business plans focus on growth, marketing, and upside.
Specialist regulatory business plans focus on:
- Compliance and risk management
- Sustainability (not aggressive growth)
- Conservative financials
- Statutory regulation adherence
- Heavy evidential support
They're fundamentally different documents serving different gatekeepers.
Yes. We support completing the regulatory application portal or form to ensure consistency between the portal responses and the narrative in the business plan, as inconsistencies between the two are a common reason for additional information requests or refusals. This service is included in the Premium tier and available as an add-on at the Standard tier.
Yes — and this is how the majority of our regulatory work is delivered. We operate as a specialist documentation subcontractor alongside immigration solicitors, healthcare management consultants, FCA compliance advisers, and commercial property solicitors. We accept the brief from your adviser, coordinate with their team directly, and produce documentation that supports their overall legal or compliance strategy.
If you do not yet have a specialist adviser for your regulatory application, we can provide referrals to regulated professionals in each sector with whom we have established working relationships.
We regularly support applications for:
Healthcare & Social Care:
- Care Quality Commission (CQC)
- Care Inspectorate Wales (CIW)
- Care Inspectorate Scotland
Education & Childcare:
- Ofsted (England)
- Estyn (Wales)
- Care Inspectorate (Scotland - childcare)
Financial Services:
- Financial Conduct Authority (FCA)
- Prudential Regulation Authority (PRA)
Immigration:
- Office of the Immigration Services Commissioner (OISC)
Other Specialist Sectors:
- Gambling Commission
- Food Standards Agency (manufacturing)
- Local Authority licensing (various)