
Start Up Loans Business Plans: Built to the British Business Bank Assessment
A Start Up Loans application is closer to a credit assessment than an investment pitch. The adviser is testing whether the plan is coherent, whether the numbers are yours, and whether your personal survival budget shows you can live while the business finds its feet.
Applications fail on those three things far more often than on the idea. We write the plan and the survival budget to the assessment itself, so the adviser can approve it without coming back with questions.
Most start-up loans fail because founders submit investor-style business plans emphasising disruption and aggressive growth. Start Up Loans assessors at the British Business Bank's delivery partners are not evaluating venture-scale returns. They are evaluating three things: personal commitment, repayment capacity, and business viability in your specific local market.
We have prepared Start Up Loans plans for UK applicants since 2014, with a 79% approval rate across our engagements. Plans are formatted to meet British Business Bank delivery partner requirements, with conservative financial projections, locally sourced market evidence, a documented personal survival budget, and explicit positioning around the mentoring relationship that follows approval.
Book a free 30-minute Start Up Loans consultation. We will assess your eligibility, discuss your concept, and explain exactly how we will structure the plan to maximise the probability of approval. No obligation.
Who Delivers This Service
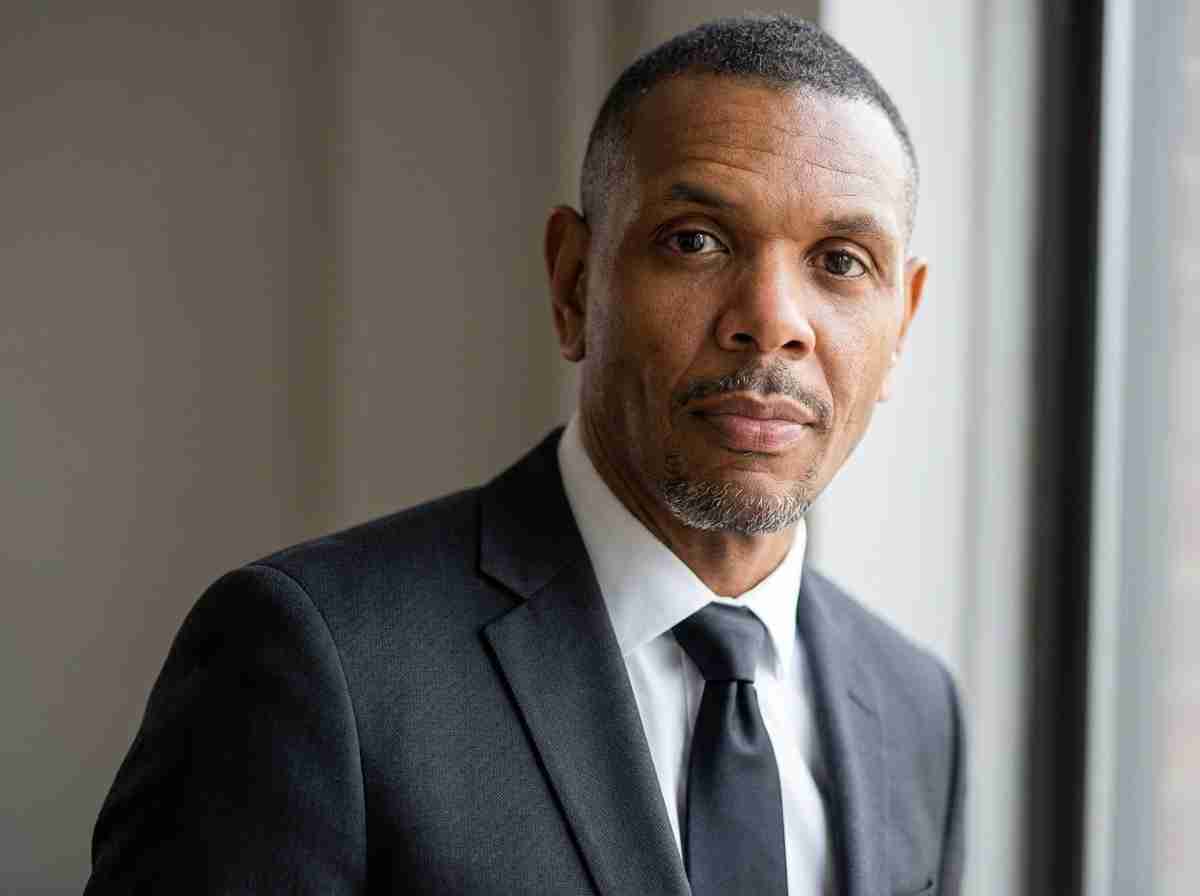
Your Start Up Loans application will be led by Kurt Graver — Accountant, MBA, Founder of SGI Consultants — supported by a qualified team with extensive experience across British Business Bank applications. Kurt personally oversees every Start Up Loans engagement, consistently achieving above-average approval rates across all sectors.
Start Up Loans Success Rate
We don't guess at British Business Bank requirements. We rely on a track record of successful Start Up Loans approvals across diverse business sectors.
Approval Rate (vs 65% national avg)
Applications Supported
Day Turnaround (Standard Service
Average Loan Amount Secured
Why Start Up Loan Applications Get Rejected
The delivery partners who assess applications have reviewed tens of thousands of business plans. They see the same mistakes repeatedly, and the most common ones are avoidable with the right guidance.
Generic investor-style projections. A business plan that opens with a market size of £2 billion and projects capturing 0.5% within two years will be rejected before the assessor reads the financial model. Delivery partner assessors know what credible first-year revenue looks like for a café, a trades business, a childminder, or a freelance consultant — because they have reviewed hundreds of each. Projections that sit significantly above the norm for the business type are treated as evidence of inexperience rather than ambition.
No personal survival budget. This is a unique requirement of the Start Up Loans scheme that most general business plan writers do not include. Assessors need confidence that the applicant can cover their personal living costs — rent, bills, food, transport — during the period before the business can pay an adequate salary. An applicant who cannot demonstrate financial resilience during the ramp-up period is a higher repayment risk. We include a detailed personal survival budget in every Start Up Loans plan that we produce.
Insufficient local market validation. Generic statements about industry growth do not satisfy delivery partner assessors. They want evidence of demand in the specific local market where the business will operate — competitor analysis with named local businesses, pricing benchmarks, evidence of customer interest such as pre-orders or letters of intent, and demographic data relevant to the target catchment. A business plan that cites national industry statistics without grounding them in local evidence fails the viability test.
Zero personal contribution or commitment evidence. Applications that show the loan covering 100% of the start-up investment with no personal financial contribution rarely succeed. Assessors look for evidence that the applicant has skin in the game — personal savings deployed, equipment purchased, time invested before the application. This does not need to be large, but it needs to be present. We help applicants identify and document their existing contributions in a way that satisfies this assessment criterion.
Repayment capacity not evidenced. The business plan must demonstrate that the monthly loan repayments are affordable given projected business cash flow and the applicant's personal financial position. We build month-by-month cash flow models that explicitly show the repayment line and prove serviceability even in a stress scenario — typically a 20% revenue shortfall against the base projection.
Why SGI — Not a DIY Template, Not a Generic Business Plan Writer
The British Business Bank publishes a free business plan template for Start Up Loans applicants. Many applicants complete it themselves or use a generic online business plan tool. These approaches fail at a predictably higher rate — the national average approval rate of approximately 65% reflects the standard of documentation most applicants submit.
Generic business plan writers produce commercially formatted documents that may be well-written but are not scheme-specific. They do not understand the personal survival budget requirement, the mentoring commitment expectation, or the local market validation standard that delivery partner assessors apply. They produce plans that look professional but fail the specific criteria that determine whether the loan is approved.
SGI Consultants has been working with Start Up Loans delivery partners for 12 years. We understand what each major partner's assessors look for, how they evaluate financial projections, and what they consider adequate local market evidence for different business types. Our 85% approval rate — against the 65% national average — reflects the specificity of our approach. We do not use templates. Every plan is built around the applicant's specific business, location, and personal financial position, structured to answer the delivery partner's assessment criteria directly.
Who We Work With
Start Up Loans applicants come from very different starting points, and the documentation challenge differs depending on the applicant's background, business type, and financial position. The people we support most frequently are:
First-time entrepreneurs launching a trade or service business. You are setting up as a sole trader — a plumber, electrician, cleaner, childminder, personal trainer, or similar — and you need the loan to cover tools, equipment, or initial working capital. Your business model is straightforward, but you have never written a business plan, and you are unsure how to demonstrate local demand and personal capability in a way that satisfies an assessor. Our Basic plan is designed for exactly this profile.
Redundant or career-changing professionals starting a consultancy or freelance practice. You have left employment and are setting up a professional services business — consulting, marketing, design, coaching, accounting, or similar. You have relevant professional experience but limited business ownership history. The challenge is demonstrating that you can convert your skills into a client base quickly enough to service the loan while covering personal living costs. We help you position transferable experience as genuine business capability and build a client acquisition model that is credible to an assessor.
Young entrepreneurs launching their first business. You are under 30, possibly applying for the first time, and you may have limited credit history or savings to contribute. The Start Up Loans scheme is specifically designed to be accessible to younger applicants, and delivery partners are experienced in evaluating early-career business cases. We help you structure the application to emphasise the strengths of a younger applicant's case — energy, digital capability, recent training or education — while addressing the areas where limited experience needs to be explained rather than hidden.
Applicants with adverse credit history. Start Up Loans considers applicants with adverse credit, but the application must directly address the circumstances of their credit history. An assessor who discovers a CCJ or missed payments without any contextual explanation will reject the application. We help applicants with credit challenges to frame the circumstances honestly and demonstrate the financial rehabilitation required by the scheme's guidelines.
Entrepreneurs who have already been rejected. You submitted a DIY application or used a template service and were declined. The rejection letter will specify the grounds — most commonly unrealistic projections, insufficient local market evidence, or an absent or inadequate personal survival budget. We review the rejection, identify the specific deficiencies, and rebuild the plan to address them directly. A significant proportion of our work involves resubmissions, and our resubmission approval rate is high because we address the assessor's specific citations rather than simply resubmitting a cosmetically improved version of the same document.
If your situation is not described above, contact us. We have supported Start Up Loans applications across virtually every business type and applicant profile over the past 12 years.
Our Start-Up Loans Business Plan Methodology
Our approach is structured around the four criteria that delivery partner assessors apply consistently across all Start Up Loans applications. These are not our invention — they are the framework the British Business Bank publishes for its accredited delivery partners.
1. Conservative Financial Modelling
Start Up Loans assessors have reviewed thousands of financial projections. They know what is realistic for a new café, a trades business, a retail shop, or a digital service. Projections that assume immediate full-capacity trading, hockey-stick revenue growth, or margins exceeding sector norms are instantly challenged.
We build models that assume a two- to three-month pre-revenue period for setup, a gradual revenue ramp-up from a realistic starting point, higher first-year marketing and customer acquisition costs, and a 10–15% buffer for unexpected expenses of total projected costs. We then model the loan repayment line explicitly and stress-test it against a 20% revenue shortfall — demonstrating that repayments remain serviceable even if things go slower than planned. The principle we apply is that it is better to exceed conservative projections than to fall short of optimistic ones.
2. Local Market Validation
Generic market research does not satisfy delivery partner assessors. Citing national industry reports without grounding them in local market evidence is one of the most consistent reasons for rejection. We provide location-specific validation for every application: demographic analysis of the applicant's catchment area using ONS data, a named competitor audit with addresses, pricing, and observed strengths and weaknesses, customer evidence where available (survey results, pre-orders, letters of intent), and trend data from government statistics relevant to the local economy.
For businesses serving a local catchment — cafés, retail shops, trades, childcare providers, fitness instructors — the local market evidence is more important than the national industry size. For businesses that operate remotely or nationally, we validate the specific customer segment and acquisition channel rather than the geographic market.
3. Personal Survival Budget
This is a requirement that makes the Start Up Loans scheme distinct from every other business lending product, and that generic business plan writers consistently omit. The delivery partner assessor needs to understand how the applicant will cover their personal living costs — rent or mortgage, household bills, food, transport, and existing debt repayments — during the period between application and the point at which the business can pay an adequate salary.
An applicant who cannot demonstrate a credible personal financial plan for the ramp-up period is a higher default risk, because financial pressure at home is one of the primary reasons early-stage businesses are abandoned before they become profitable. We build a detailed personal survival budget into every Start Up Loans plan — documenting monthly personal outgoings, the source of funds to cover them during the pre-salary period (savings, partner income, part-time employment), and the timeline to when the business can reasonably pay a living wage. This section is not glamorous, but it is often the difference between approval and rejection.
4. Mentoring Readiness and Personal Commitment
Start Up Loans includes 12 months of free business mentoring, and the scheme's guidelines require applicants to demonstrate awareness of and commitment to this support. Assessors look for evidence that the mentoring will be used actively — specific areas where the applicant recognises the need for guidance, a commitment to regular engagement with the mentor, and a willingness to implement recommendations.
Beyond the mentoring requirement, the personal commitment narrative — why this applicant is capable of making this specific business succeed — is weighted more heavily in Start Up Loans assessments than in any other business lending context. We help applicants articulate their relevant experience, transferable skills, and personal motivation in a way that demonstrates genuine capability without overstating it. Authenticity matters here: assessors who read hundreds of applications develop a keen sense of whether a personal narrative is genuine or constructed.
Book A Strategic Assessment and Business Plan Evaluation
Start Up Loans Business Plan Pricing
We offer a specialised, fixed-fee service specifically structured for Start Up Loans requirements. Our pricing reflects the standardised nature of Start Up Loans applications compared to complex investor or grant documentation.
From
Basic Start Up Loans Plan
What's Included:
- Core Business Plan (15-20 pages)
- 2-Year Financial Projections
- Basic Market Analysis
- Use of Funds Breakdown
- Editable Source Files
Delivery Time: 5-7 business days from information receipt
Perfect for: Straightforward businesses with simple financial models (e.g., sole traders, service businesses, trades)
Standard Start Up Loans Plan
What's Included:
- Comprehensive Business Plan (25-35 pages)
- 3-Year Financial Projections
- Detailed Market Research
- Use of Funds Breakdown
- Risk Assessment
- Supporting Documents Coordination
- Dedicated Start Up Loans Specialist
- Editable Source Files
Delivery Time: 7-10 business days from information receipt
Perfect for: Most Start Up Loans applications requiring comprehensive documentation (e.g., retail, hospitality, small manufacturing)
Premium Dual-Track Plan
Everything in Standard Plan, PLUS:
- Second Business Plan: Bank-Ready Version (35-45 pages)
- Enhanced Financial Modelling
- Dual-Purpose Market Research
- Strategic Growth Roadmap
- Priority Support
- Extended Post-Delivery Support
Delivery Time: 10-14 business days from information receipt
Perfect for: Businesses pursuing Start Up Loans but wanting bank-ready documentation for future growth funding
What's Included in Your Investor Business Plan Package
Feature | Basic | Standard | Premium |
Price | £400 | £700 | £1,200 |
Business Plan Pages | 15-20 | 25-35 | 25-35 + 35-45 (bank) |
Financial Projections | 2 years | 3 years | 5 years (multi-scenario) |
Competitor Analysis | 2-3 | 3-5 | 5-8 (professional data) |
Personal Survival Budget | ✗ | ✓ | ✓ |
Risk Assessment | Basic | Comprehensive | Comprehensive |
Supporting Documents Guidance | ✗ | ✓ | ✓ |
Dedicated Specialist | Email only | Email/Phone | Priority access |
Revision Rounds | 1 | 2 | 3 |
Bank-Ready Plan Included | ✗ | ✗ | ✓ |
Growth Roadmap | ✗ | ✗ | ✓ |
Professional Database Research | ✗ | ✗ | ✓ |
Post-Delivery Support | 14 days | 30 days | 60 days |
Delivery Time | 5-7 days | 7-10 days | 10-14 days |
Which Tier is Right For You?
Choose Basic if:
- Your business model is straightforward (sole trader, simple service business)
- You have strong business experience and confidence in your concept
- Budget is a primary constraint
- You're comfortable with streamlined documentation
Choose Standard if:
- You want the best chance of Start Up Loans approval (our most popular option)
- Your business has moderate complexity (retail, hospitality, trades)
- You want comprehensive documentation that addresses all British Business Bank criteria
- You value dedicated specialist support throughout the process
Choose Premium if:
- You're thinking beyond Start Up Loans to future growth funding
- You want to avoid recreating documentation in 12-24 months
- Your business has scaling potential requiring £50k-£250k+ capital
- You want bank-ready documentation from day one
- You value long-term strategic planning alongside immediate funding needs
90% of our clients choose Standard - it provides the optimal balance of comprehensiveness and value for most Start Up Loans applications.
Premium saves you £800+ compared to commissioning a Start Up Loans plan now (£700) and a separate bank business plan later (£2,500) - while ensuring perfect consistency between both documents.
Explore Further
Related reading:
- Grants and R&D Tax Credits: Unlocking Hidden Funds — Other government funding options alongside Start Up Loans
- Business Plans: Insights from 500 Evaluated Cases — Why most applications fail and how to avoid the common mistakes
- Executive Summary Guide: Secure Funding — How to write the section assessors read first
Free resource:
- The Business Plan Template Masterpack → — Templates built around the British Business Bank's requirements
Content hub:
- Business Funding & Finance Hub → — Complete guides to government-backed funding schemes
Related services:
- Business Plan Writers — All business plan types covered
- Bank Loan Business Plans — For high street and commercial lending
- Business Startup Planning & Formation — Complete startup support beyond the funding application
Start Up Loans Applications We Have Turned Around
Real Application Outcomes
The café resubmission — from rejection to £15,000 in three weeks: A café entrepreneur had submitted a DIY business plan projecting £180,000 in first-year revenue. The delivery partner rejected the application, noting that the revenue projection was not credible for a new café at the proposed site and that no evidence of local competitor pricing had been provided. We rebuilt the plan from scratch: revenue projections were revised to £95,000 based on local footfall data and a competitor pricing analysis of six nearby cafés, a detailed equipment cost breakdown was added (coffee machine, grinder, furniture, POS system), and a personal survival budget was included showing the owner's savings covering three months of living costs while the business ramped up. The application was approved for £15,000 within three weeks of resubmission.
The trades start-up — first-time applicant approved at full amount: A recently qualified electrician leaving employment to set up his own electrical contracting business applied for £20,000 to cover a van, tools, and initial working capital. He had no prior business ownership experience and modest personal savings. We built the plan around his apprenticeship and three years of employed trade experience, conducted a local competitor audit of 11 electrical contractors within his target area (identifying a gap in domestic EV charger installation where local competition was limited), and constructed a conservative client acquisition model based on realistic quote-to-conversion rates. The personal survival budget showed eight months of living cost coverage through his partner's income and a small personal savings reserve. First application approved for the full £20,000.
The career—changer—consultancy launch after redundancy: A marketing director made redundant from a corporate role applied for £15,000 to launch an independent marketing consultancy. The challenge was demonstrating that 20 years of employed marketing experience would translate into a client base quickly enough to service the loan. We built the plan around two confirmed client commitments she had secured before applying (as evidenced by letters of intent), a network-based client acquisition model, and a personal survival budget showing six months of living-cost coverage through her redundancy payment. The application was approved within the standard 14-day processing window.
Further case study examples available across: trade businesses | retail and hospitality | online and digital services | professional and personal services | creative industries
Explore detailed examples of how our business planning has enabled clients to secure funding and achieve growth:
Read Our Complete Case Studies & Track Record →
Ready to Access Government-Backed Funding?
The Start Up Loans scheme provides genuinely accessible capital for UK entrepreneurs who cannot access traditional lending. The barrier is not eligibility — it is documentation. A business plan that speaks the delivery partner's language, addresses the scheme's specific assessment criteria, and demonstrates realistic financial sustainability will outperform a generic plan regardless of the underlying quality of the business idea.
Schedule a Free Start-Up Loans Assessment today. In this 30-minute call, we will confirm your eligibility for the scheme, assess your business concept against the delivery partner's criteria, and explain exactly how we would structure your application to maximise the probability of approval.
If we assess that your business concept needs further development before a Start Up Loans application is viable — because the market evidence is insufficient, or the personal financial position does not support the repayment burden — we will tell you that directly.
Frequently Asked Questions (FAQs)
Yes. The Start Up Loans scheme supports part-time business launches. However, the business plan must address how you will manage both commitments — demonstrating realistic time allocation for the business alongside your employment — and should include a timeline for transitioning to full-time business operation if that is your intention.
The personal survival budget is straightforward for applicants still in employment, since your salary covers living costs. However, the plan must explain how you will service the loan if your employment income is your primary source of repayment during the early period, since the loan is a personal liability regardless of business performance.
Start Up Loans considers applicants with adverse credit history, including CCJs, missed payments, or previous insolvency. However, the application must address the credit history directly and transparently. An assessor who discovers adverse credit without any contextual explanation in the application will treat it as a red flag. An assessor who reads a clear, honest account of the circumstances and the steps taken since will treat it as a managed risk.
We have significant experience in preparing applications for clients with credit challenges. The key is framing — acknowledging the history honestly, explaining the circumstances briefly and factually, demonstrating the financial rehabilitation that has taken place, and ensuring the business plan itself is strong enough to give the assessor confidence in the applicant's current position.
No. Start Up Loans does not require personal guarantees or collateral. However, you are personally liable for repayment (like any loan).
The maximum per individual applicant is £25,000. However, if the business has multiple co-founders or directors, each person can apply for up to £25,000 individually, with a combined maximum of £100,000 per business. Each co-founder must submit their own application and their own business plan sections covering personal capability and personal financial position, while the business sections (market analysis, financial projections, operations) can be shared.
If your business requires more than £25,000 from the outset, it is worth considering whether the Start Up Loans scheme is the right primary funding vehicle, or whether a commercial bank loan or hybrid approach (Start Up Loan plus bank lending) is more appropriate. We can advise on this during the initial assessment.
Start Up Loans expects repayment but understands business challenges. If you face difficulties:
- Contact your delivery partner immediately
- Discuss repayment plan adjustments
- Seek free business support/mentoring
Deliberate non-payment can result in debt collection and credit rating impact.
No professional can guarantee a third-party lending decision, and any service that does is misrepresenting what is possible. Approval depends on factors beyond the documentation — including the delivery partner's current capacity, the applicant's credit profile, and assessor judgment on personal suitability.
Our 79% approval rate, compared with the national average of 65%, demonstrates that our documentation consistently meets the British Business Bank's criteria. Where applications are declined specifically due to deficiencies in the business plan we produced, we provide resubmission support at a significantly reduced rate. If applications are declined for reasons outside the plan — such as credit history, eligibility, or delivery partner capacity — we will help you understand the reasons and advise on next steps.
Start Up Loans assessment focuses on:
- Personal capability (more than traditional banks)
- Viability (sustainability over aggressive growth)
- Social impact (job creation, community benefit)
Commercial bank loans focus on:
- Security/collateral
- Credit history
- Trading history/accounts
Start Up Loans is more accessible but requires demonstrating personal commitment more explicitly.